
Women's World Banking: Alternative Credit Scoring Must Prioritise Consumer Data Protection
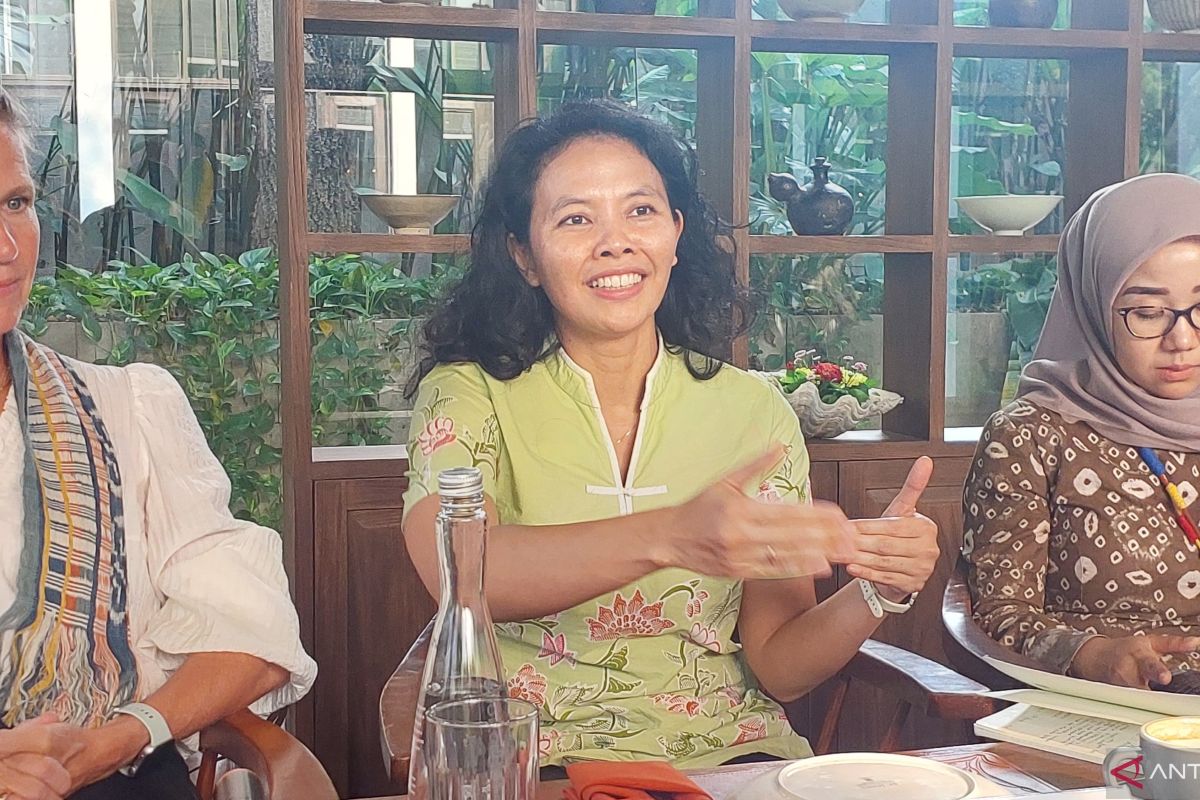
The use of alternative data must take into account user consent as well as personal data protection.
Jakarta (ANTARA) - Vitasari Anggraeni, Director of Southeast Asia Policy at Women’s World Banking, said the development of alternative credit scoring continues to prioritise personal data protection and consumer consent, so that access to financing for micro, small and medium enterprises (MSMEs) can be expanded without sacrificing data security.
Vita said the use of alternative data for credit assessment must be carried out responsibly, particularly because it involves the personal data of micro and ultra-micro business owners.
“The use of alternative data must consider user consent as well as personal data protection. That is why we are testing this model together with financial institutions and regulators to ensure it complies with applicable regulations,” Vita said during a media discussion on alternative credit scoring in Jakarta on Thursday.
She said Women’s World Banking, together with regulators and financial institutions including PT Permodalan Nasional Madani (PNM), is currently testing the implementation of alternative credit scoring to ensure the model is safe, compliant with regulations, and able to expand access to productive financing for MSMEs.
According to her, the use of alternative data aims to build the digital footprint of MSME players from the outset through their activity on digital financial services. Such digital traces — savings habits, bill payments, and business transactions — can serve as the basis for creditworthiness assessments for entrepreneurs who have no borrowing history.
“When there is access to credit, to loans, it is indeed used in accordance with the purpose stated by the borrower at the beginning. That is why we need to develop further using payment data, utility data, and other data that can support responsible lending,” Vita said.
However, she stressed that alternative data cannot be the sole basis for credit assessment. Such data only serves as a supplement and must still be combined with other verification processes, including field validation by financial institutions.
“Alternative data is a complement to the credit assessment process. Field validation remains necessary to ensure the data used is accurate and matches the customer’s circumstances,” she added.
In addition, Women’s World Banking is encouraging the use of gender-sensitive data — data capable of capturing the characteristics and needs of women entrepreneurs — so that credit scoring models do not produce algorithmic bias.
According to Vita, this approach is important because the financing needs of women MSME entrepreneurs often differ from those of men, for example in terms of cash flow patterns and credit usage.
She hopes the implementation of the system will not only improve financial inclusion but also safeguard consumer data security, so that public trust in digital financial services is maintained.