
Wary of Rising Government Bond Yields
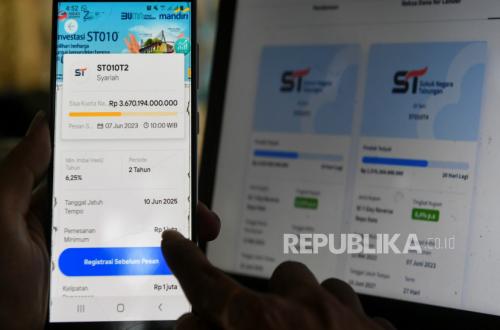
Bank Indonesia has few options left except to increase the yields offered for new Government Securities (SBN). The rise in US Treasury (UST) yields has currently reached its highest point since 2 therefore, the 10-year UST yield has continued to climb, reaching 5.31 per cent. Consequently, the 10-year Indonesian government bond (SUN) yield has been pushed up from 6 per cent at the start of 2026 to 7.17 per cent in October 2026.
It is not impossible that SBN yields will continue to rise, given that the spread between SBN and UST yields has narrowed to just 180-190 basis points. For foreign investors, such a thin spread is likely to stimulate them to move investments from Indonesia to countries considered safe havens. Experience has proven that when SBNs offered to investors do not promise attractive returns, the risk of capital flight is very high.
Bank Indonesia is currently in a dilemma. While raising the interest rates offered on SBNs is an unavoidable step that must be taken, it is not without risk. What must be done now is to anticipate potential risks and ensure that the impact does not create new problems that further damage the national economy.
In theory, government bond yields move up or down based on the laws of supply and demand in the secondary market and expectations regarding benchmark interest rates. It is common for investors to demand higher yields so that their real returns are not eroded by the rate of inflation.
In the global market, the primary benchmark for investors is the influence of US Treasuries. An increase in US Treasury yields often triggers capital flight from emerging markets to the United States. In practice, Indonesian SBNs often have to raise yields to remain attractive to foreign investors and maintain the spread. Investors tend to compare the two to see the difference. Because Indonesia’s risk is considered higher than that of the US, SBN yields are usually higher than US Treasuries.
Currently, global investors are engaging in mass selling or demanding higher risk premiums due to three main factors. Central banks worldwide are forced to maintain benchmark interest rates at high levels to combat persistent inflation. Not only in Indonesia, but inflation in the US is also exerting pressure, forcing the Fed to raise benchmark interest rates. Many countries are held hostage by high interest rates for a long period, at least until the end of 202 and due to inflationary pressures.
For developing countries like Indonesia, the decision to raise SBN yields often leads to an expanding fiscal deficit. The government is forced to act aggressively by issuing new debt to finance state spending. As a result, the market experiences an oversupply of bonds, which ultimately burdens our fiscal condition.
Amidst uncertain geopolitical conditions and global uncertainty haunting various nations, investors are demanding higher compensation in yields to hold long-term assets. At this point, countries may have no choice but to increase the yields offered.
For countries with robust resilience, an increase in government debt yields may not have a significant impact. However, for Indonesia, the decision to raise SBN yields is not without risk. The rise in government debt yields is not an isolated phenomenon on the trading floor; it has a real destructive power that spreads directly to the real sector through several channels.
First is the risk of ballooning debt costs (refinancing risk). For the government, rising bond yields certainly mean that the cost of borrowing money becomes much more expensive. When old bonds mature, the government must issue new bonds with higher yields. Consequently, the portion of the State Budget (APBN) allocated solely to paying interest (debt service) will swell, eating into budgets for productive spending such as energy, health, and education subsidies.
The government estimates that total debt interest payments until the end of 2026 will reach Rp599.24 trillion. In 2027, this burden is projected to surge to Rp650.31 trillion. As of August 2026 alone, the amount of the State Budget absorbed for interest instalments reached Rp394.2 trillion. This is certainly not a light burden.
Second is the ‘crowding out’ effect of rising bond yields on the private sector. The banking and corporate sectors use government bond yields as a benchmark to determine their credit interest rates. If government bond yields reach high levels, banks will raise loan interest rates for businesses and consumers. Capital becomes expensive, business expansion stalls, and economic growth projections slow down. The private sector is ‘crowded out’ of the capital market because it cannot compete with state instruments that are considered safer yet offer high returns.
Third is the pressure on the currency exchange rate and the potential for capital outflow. If a surge in yields is initiated by a superpower like the US (US Treasury), the risk is a phenomenon of global capital suction. Institutional investors will withdraw their funds from emerging markets to chase risk-free returns in the West. This triggers the depreciation of local currency, which in turn increases the cost of imported raw materials (imported inflation).
Source: jawawa.id (https://jawawa.id/newsitem/wary-of-rising-government-bond-yields-1791359876)
Originally published by Republika (https://analisis.republika.co.id/berita/tmiyay393/mewaspadai-kenaikan-yield-surat-utang), translated from Indonesian