
Video: The Credit Scoring Revolution, How Technology Evaluates Customer Profiles
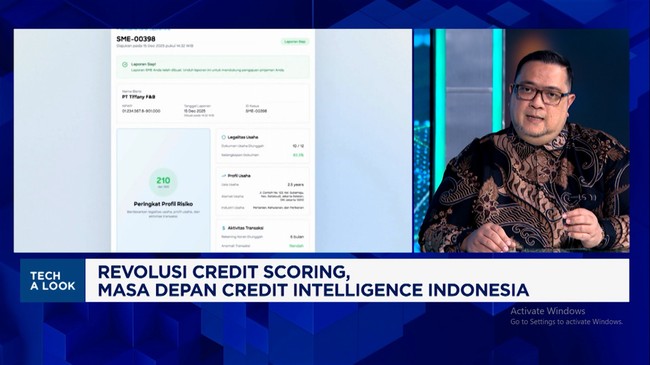
Developments in digital technology are altering the direction of credit scoring management within the processes of data verification and credit risk assessment for prospective customers. Automation and big data analytics are assisting credit information management institutions (LPIP) or credit bureaus in providing faster and more accurate assessments of customer eligibility, thereby accelerating credit decision-making.
Credit Bureau Indonesia (CBI), acting as a credit bureau company, is also utilising digitalisation to provide more accurate credit data. This includes debt history, credit transactions, and payment transactions, which can be utilised by lenders such as banks, fintech firms, P2_P lending platforms, and multi-finance companies.
The President Director of Credit Bureau Indonesia (CBI), Anton K. Adiwibowo, stated that technology has transformed credit scoring from being solely based on historical data to incorporating credit behaviour combined with alternative data. Furthermore, the use of machine learning in data processing results in superior risk profile data.
CBI is encouraging the large-scale utilisation of credit data through machine learning via its credit intelligence platform solution. This allows organisations, such as credit providers, to collect, process, and utilise credit data for making decisions regarding a customer’s credit risk.
How is the credit scoring revolution and the use of credit intelligence unfolding in reading customer credit risk profiles? For more details, see the dialogue between Shafinaz Nachiar and the President Director of Credit Bureau Indonesia (CBI), Anton K. Adiwibowo on Profit, CNBC Indonesia (Monday, 21/09/2026).