
Three Months Before PSPK 1 and 2 Take Effect, Issuers Must Prepare Sustainability Data Systems
Indonesian issuers have approximately three months to prepare sustainability data and disclosure processes before the Sustainability Disclosure Standard Statements (PSPK) 1 and 2 become effective for annual reporting periods starting 1 January 2027. These standards, developed by the Sustainability Standard Board of the Indonesian Institute of Accountants (DSK IAI), demand sustainability data that is traceable to source documents and linked to financial statements.
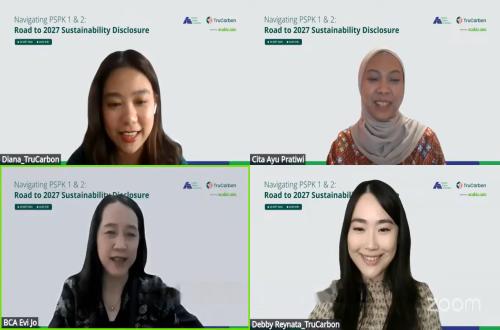
Consequently, companies are advised to immediately build data collection systems. This was highlighted during the seminar ‘Navigating PSPK 1 & 2: Road to 2027 Sustainability Disclosure’, organised by TruCarbon in collaboration with the Indonesian Issuers Association (AEI) on Wednesday (30/09/2026).
AEI Executive Director Gilman Pradana Nugraha reminded participants that data readiness is the primary task for issuers. “Sustainability disclosure is becoming increasingly integrated with financial reporting and investor decision-making. It is vital for us to ensure that data is complete, integral, has clear governance, and clear internal ownership; that the data collection process is valid and reliable, and that there is connectivity between the sustainability team and other departments,” he stated.
This is more than just a change in reporting format. The obligation to publish sustainability reports is not new; the Financial Services Authority (OJK) has mandated it for issuers, financial institutions, and public companies since 2019 through POJK 51/2017. What has changed is the technical standard for its preparation.
PSPK 1 and 2, ratified by DSK IAI on 1 July 2025, adopt IFRS S1 and IFRS S2 from the International Sustainability Standards Board (ISSB). Cita Ayu Pratiwi, a member of the IAI Sustainability Working Team, explained that PSPK 1 serves as the general framework governing what must be included in sustainability reporting, while PSPK 2 regulates specific climate-related disclosures.
Both standards share four core contents: governance, strategy, risk management, and metrics and targets. Moving forward, these standards will continue to evolve through PSPK 3, 4, and 5 to capture other sustainability risks and opportunities beyond climate change.
She added that the PSPK is designed as an investor-focused standard to produce globally comparable information. The primary users are current and potential investors, lenders, and other creditors, who use this information to decide whether to buy, sell, or hold shares and debt instruments, or to provide loans.
According to Cita, the PSPK introduces a different perspective from previous sustainability reporting. “Previously, the perspective might have been how a company impacts the external environment, social, or governance aspects, but this time we are shifting the view to see how those aspects impact the company internally,” she said.
To begin preparations, Cita suggested that companies should not start by asking what needs to be disclosed. Instead, companies first need to assess whether their current processes are adequate to support effective sustainability disclosure and implementation.
From the issuer’s perspective, Evi Jo, Head of Sustainability & CSR Subdivision at PT Bank Central Asia Tbk (BCA), shared how BCA integrates cross-departmental work in preparing sustainability reports. She noted that implementing PSPK requires collaboration across divisions, particularly between the sustainability, risk, business, and accounting teams.
For BCA, the sustainability report is a form of accountability, not merely an effort to appear good through polished writing. The report reflects the implementation of BCA’s sustainability commitments and serves as the company’s responsibility to investors as an issuer.
Regarding the 90-day plan before the 2027 fiscal year, TruCarbon Director Debby Reynata stated that the remaining 90 days of 2026 are a critical period for preparing for the 2027 fiscal year under PSPK 1 and 2. She recommended three stages.
The first stage, days 1 to 30, should be used to define the entity’s scope in alignment with the financial report’s consolidation boundaries and governance. The second stage, days 31 to 60, involves building a ‘data engine’—mapping data activities at every location, including sources, units, frequency, and responsible parties. The third stage, days 61 to 90, involves a ‘dry run’.
“We recommend conducting a dry run using data from the previous year,” said Debby. This trial serves as a way to identify data gaps early before they emerge during the assurance process. “These 90 days are sufficient to ensure that the 2027 fiscal year begins with an operational system or SOP.”
She also noted the three-year relief for Scope 3 emissions disclosures (indirect emissions from a company’s value chain). While this period is longer than the one-year relief provided by IFRS, the delay applies only to disclosure, not to data collection. Scope 3 data must still be collected regularly starting now, as quality improves only after several reporting cycles and requires supplier engagement.