
Strong Performance Sends Antam Shares to Lofty Price Targets
PT Aneka Tambang Tbk (ANTM), known as Antam, posted a 46% increase in net profit to Rp9.66 trillion through September 2026, supported by revenue growth of 23% to Rp88.48 trillion. Several brokerages believe the company’s strong performance will continue through the end of 2026 and have set high price targets for ANTM shares.
During the period, EBITDA rose 45% to Rp13.48 trillion, while operating profit increased 53% to Rp12.05 trillion.
The company’s total assets reached Rp59.74 trillion, up 24%. Equity grew 17% to Rp41.22 trillion, cash and cash equivalents stood at Rp10.54 trillion, and net cash generated from operating activities was Rp5.06 trillion.
Cash receipts from customers totalled Rp87.92 trillion, an increase of 29%, in line with sales growth and effective working capital management.
Phintraco Sekuritas said Antam’s performance through September 2026 remained in line with its estimates, with downstreaming serving as the main growth catalyst. The brokerage expects a combination of solid average selling prices (ASPs) and higher sales volumes to lift Antam’s 2026 revenue by 43% to Rp120.93 trillion.
As a result, 2026 EBITDA is forecast to rise 67.4% to Rp16.12 trillion. Alongside EBITDA growth and increased contributions from associates, particularly PT Bintan Alumina Indonesia (BAI) and PT Weda Bay Nickel (WBN), Phintraco Sekuritas expects Antam’s full-year net profit to reach Rp11.65 trillion, up 61.6% from its 2025 result. The brokerage retained its buy recommendation on ANTM shares, with a fair value of Rp4,840, implying price-to-earnings ratios of 10 times for 2026 and 9.6 times for 2027.
Sucor Sekuritas analyst Andreas T said Antam’s net profit this year would be supported by nickel ore sales and higher selling prices. Low capital expenditure would also allow the company to convert net profit into cash.
He forecasts net profit of Rp10 trillion this year, with free cash flow (FCF) of around Rp9–10 trillion in 2027. Capital expenditure next year is expected to be only Rp1.5 trillion.
“This creates sufficient room to support investment growth while also providing returns to shareholders,” he said in a research note on Thursday, 29 October 2026.
Assuming a dividend payout ratio of 65%, he forecasts ANTM’s dividend yield could reach 10%, potentially providing a floor for the share price. The fundamentals of its commodity business also remain highly supportive, he said.
Sucor maintained its buy recommendation on ANTM shares, with a high price target of Rp5,500, based on a price-to-earnings ratio of 5.4 times.
Antam President Director Untung Budiharto said the company’s solid performance through September 2026 reflected strong business fundamentals and the effectiveness of its strategy to maintain operational performance and profitability.
“The continued growth in performance reflects Antam’s commitment to consistently transform the company in support of sustainable long-term business growth,” Untung said.
Antam Finance and Risk Management Director Arini Kasmira said the positive performance through September demonstrated the company’s ability to optimise business growth while maintaining financial discipline.
Through effective working capital management, ongoing cost control and measured risk management, Antam had strengthened profitability and maintained sound financial fundamentals amid market volatility, she said.
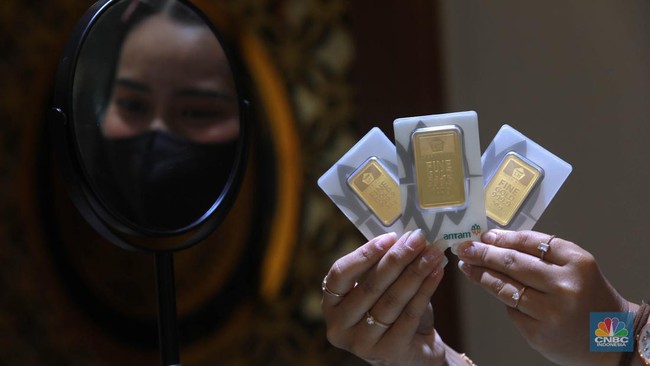
Gold products were Antam’s largest sales contributor, accounting for 77% of total sales during the period. Gold sales rose 17% to Rp68.41 trillion as of the end of September.
Nickel products, comprising ferronickel and nickel ore, accounted for 19% of total sales. Revenue from the nickel segment reached Rp16.98 trillion, up 52% from Rp11.15 trillion in the same period a year earlier.
The bauxite and alumina segment contributed 3% of total sales, with revenue of Rp2.64 trillion, up 35% from Rp1.95 trillion.
Arini added that, alongside efforts to boost operational and financial performance, Antam was stepping up its environmental, social and governance (ESG) initiatives. The company has also developed its own ESG roadmap.
“Plans, targets and initiatives have been prepared to guide the company’s sustainability journey,” she said.
On the environmental front, Antam’s ESG targets focus on greenhouse gas emissions, wastewater and land rehabilitation. Its social priorities include improving community livelihoods, raising and maintaining safety standards, and respecting human rights and indigenous communities.