
Semen Indonesia (SMGR) Streamlines Business Through Internal Merger; Stock Prospects Analyzed
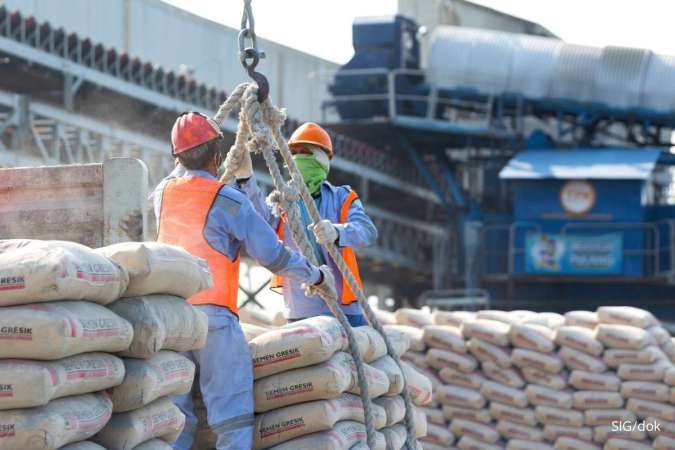
PT Semen Indonesia Tbk (SMGR) is currently reorganising its business structure through the internal merger of several subsidiaries. This move has the potential to simplify the group’s structure while creating opportunities for efficiency amidst the company’s improving performance in the first half of 2026.
Based on financial reports as of June 2026, SMGR signed two Conditional Merger Agreements on 21 August 2026. Firstly, PT Semen Indonesia Beton (SIB), PT Solusi Bangun Beton (SBB), and PT Readymix Concrete Indonesia (RCI) will be merged into PT Varia Usaha Beton (VUB).
SMGR management stated that this action is part of a group streamlining process to strengthen and integrate its portfolio of aggregates, concrete, and distribution businesses. The merger remains conditional and will only become effective after obtaining approval from the Minister of Law regarding the amendments to the articles of association for VUB and SID.
The deadline for fulfilling these conditions precedent is set for 30 September 2026, unless extended by mutual agreement between the parties.
Elandry Pratama, Analyst and Branch Manager of Panin Sekuritas Pondok Indah, assessed that this consolidation could potentially have a positive impact on group efficiency. “In the medium term, this consolidation should help reduce operating costs and improve efficiency, although the impact on margins may not be significant in the short term due to the ongoing integration process,” Elandry told Kontan.
On the other hand, SMGR’s performance is beginning to show signs of recovery. Revenue in the first half of 2026 grew by 13.1% year-on-year to approximately Rp17.64 trillion. Net profit surged by 408.9% to Rp228.25 billion, reversing from a loss of Rp8.15 billion during the same period last year.
This improvement was supported by a 5.6% increase in cement sales volume to 18.28 million tonnes. Domestic sales grew by 9.7%, while bagged cement sales increased by 11.2%. Simultaneously, net finance costs fell by 34.5% in line with a reduction in interest-bearing debt.
Elandry believes the momentum for improvement could continue in the second half of 2026, particularly if government spending and construction activities increase, demand for bulk cement recovers, and special cement exports to the United States remain steady. However, pressures from excess capacity, price competition, energy and logistics costs, and the purchasing power of the property sector remain risks.
Under the programme themed ‘Generasi Aktif Solidaritas Pesisir & Olah Lingkungan’ (GASPOL), volunteers planted 5,000 mangrove and casuarina seedlings, cleaned beaches, built nurseries, and supported coastal MSMEs through digital, branding, and marketing training. The activities also included environmental and mangrove ecosystem education for the community and students.
“The preservation of the mangrove ecosystem must be carried out sustainably by involving the community,” said SIG President Director Indrieffouny Indra.
This activity continues SIG’s efforts at Bahak Beach, where, alongside the East Java Provincial Government, 17,845 mangrove seedlings were planted in August 2025. Beyond conservation, SIG encourages the use of the area as a space for education and the economic empowerment of coastal communities through MSME development and ecotourism.
Regarding investment, the surge in profit provides a positive catalyst for SMGR shares. However, investors still need to observe whether the recovery in margins and profit can continue after the low-base effect from the previous year.
Elandry recommends ‘accumulate on weakness’ for SMGR with a price target of Rp2,100 per share. Meanwhile, Senior Analyst at Miraera Asset Sekuritas, Nafan Aji Gusta, provides a ‘hold’ recommendation with a price target of Rp1,825 per share. Conversely, industry excess capacity and price competition remain factors that investors must monitor.