
Ready to Drive National Economic Growth, Perbanas Chairman Affirms Solid Banking Fundamentals
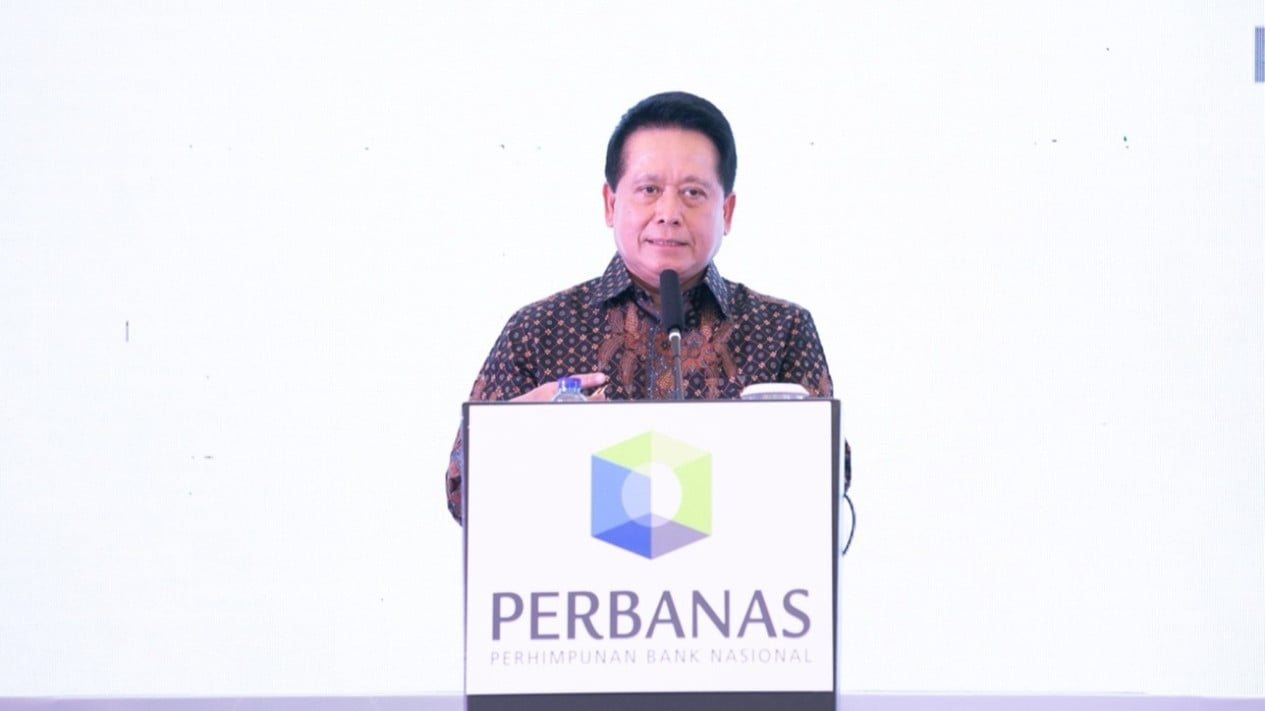
The Indonesian National Banks Association (Perbanas) assesses that Indonesia’s banking sector remains in a healthy condition amidst global and domestic economic dynamics. This is reflected in sustained strong credit growth, maintained liquidity, and adequate capital to support intermediation functions and national economic growth.
Hery Gunardi, Chairman of Perbanas and President Director of BRI, stated that the national banking sector is still capable of performing its role as an economic driver through continuous credit distribution and increasing public fund collection.
“Based on OJK data, as of the end of April 2026, banking credit distribution grew by 9.98% year-on-year, while Third-Party Funds grew by 11.40%. This shows that public confidence in the banking system remains intact and the intermediation function is operating effectively,” said Hery, as reported on Thursday, 11 June 2026.
In terms of liquidity, the Loan to Deposit Ratio (LDR) was recorded at 86.88%. Meanwhile, the Gross Non-Performing Loan (NPL) ratio stands at 2.17%. These conditions indicate that the banking industry still possesses adequate capacity to support economic financing while maintaining asset quality.
According to Hery, this performance serves as essential capital for banks to continue supporting economic activities and various national development programmes.
Nevertheless, vigilance is still required given that global uncertainty remains quite high. Geopolitical tensions, energy price volatility, and economic slowdowns in several countries have the potential to affect business activities and financial market sentiment.
“Therefore, prudent risk management, liquidity adequacy, and the quality of credit growth must remain primary focuses to ensure the industry’s resilience is maintained,” Hery explained.
To strengthen this resilience, banks need to continue enhancing various risk mitigation measures. Strengthening risk management is a vital aspect, including through the implementation of sectoral stress tests on portfolios sensitive to rising energy costs, strengthening early warning systems against potential deterioration in credit quality, and applying stricter credit discipline according to each debtor’s risk profile.
Additionally, banks must ensure liquidity adequacy to face potential market volatility and fluctuations in public funds. Such efforts can be achieved through the strengthening of liquidity indicators, including the Liquidity Coverage Ratio (LCR) and the Net Stable Funding Ratio (NSFR).