
Profit in Indonesia, Tax Elsewhere?
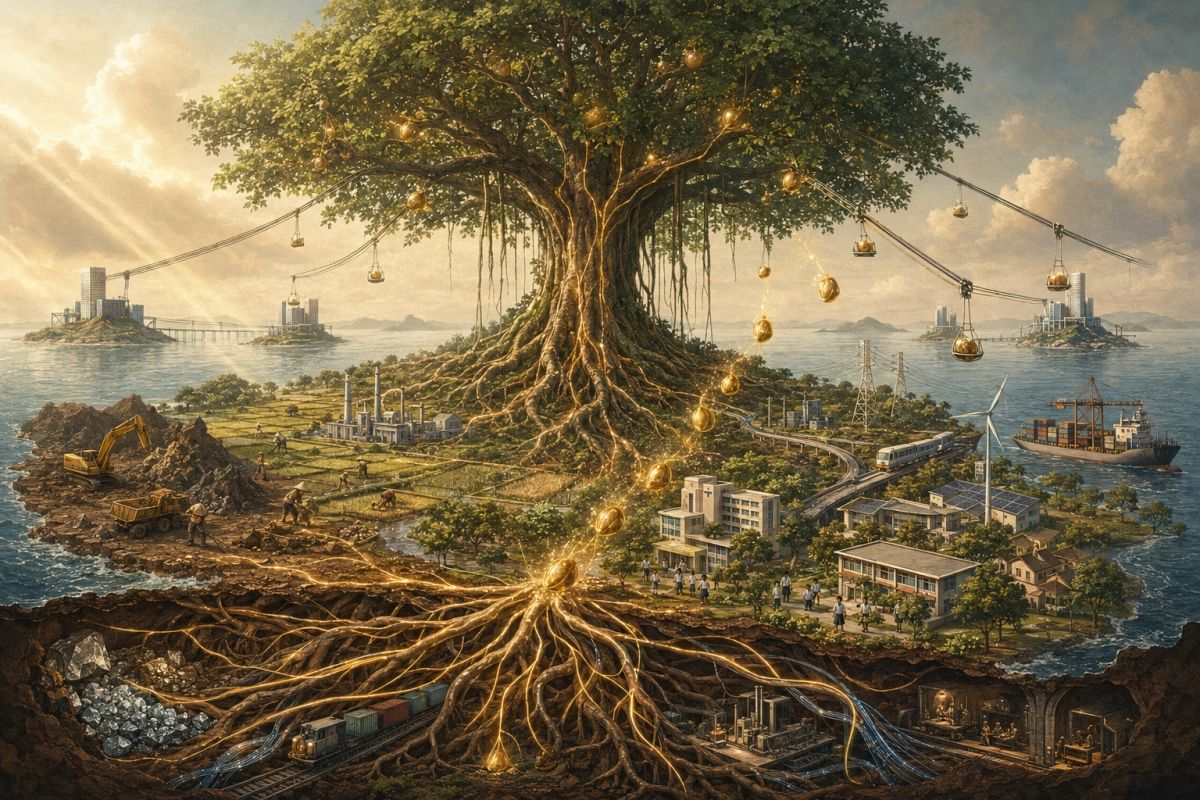
For decades, developing countries have faced a taxation paradox. Roads are built, workers are hired, natural resources are exploited, and domestic markets become a source of profit for multinational corporations.
Yet most of those profits are recorded in countries with almost no real economic activity, such as various tax haven jurisdictions. As a result, the countries where economic value is actually created lose revenue that could have been used to finance education, health, infrastructure and social protection.
The paradox stems from an international tax system that has been in place for nearly a century. The system grants taxing rights based on where a company reports its profits, not where those profits are generated.
In a modern economy underpinned by multinational corporations, intangible assets and digital transactions, such rules are increasingly out of step with reality. For that reason, the negotiations on the United Nations Framework Convention on International Tax Cooperation in New York represent an important moment to update global tax governance so that it is fairer for developing countries, including Indonesia.
The core problem is not that multinational corporations do not pay tax, but that they often pay tax in the wrong country. Through transfer pricing mechanisms, royalty payments, intercompany loans and the transfer of intellectual property rights, profits can be legally shifted to low-tax jurisdictions.
Imagine an electric vehicle company that processes nickel from Sulawesi into batteries. Its factory is in Indonesia, its workers are Indonesian, the electricity and infrastructure are provided by the Indonesian government, and its products are sold to the global market. Yet the patent rights are held in the Netherlands, the financing comes from Luxembourg, and the trading company is located in Singapore.
When all of these internal transactions are structured in such a way, the profit reported in Indonesia becomes far smaller than the economic profit actually generated. Indonesia still collects tax, but only on a small fraction of the profit that remains.
Until now, the Directorate General of Taxes has had to prove that every transaction between affiliated companies satisfies the arm’s length principle, namely the price that would have applied had the transaction been conducted by parties without a special relationship.
Source: jawawa.id (https://jawawa.id/newsitem/profit-in-indonesia-tax-elsewhere-1786096490)
Originally published by Antara (Indonesian) (https://www.antaranews.com/berita/5684175/laba-di-indonesia-pajak-di-mana), translated from Indonesian