
Perbanas Chief Speaks Candidly on Impact to Banks if BI Rate Rises
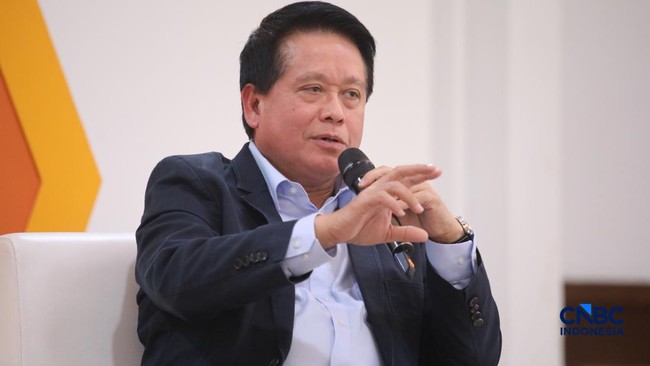
The National Banks Association (Perbanas) has stated that the banking industry’s profitability will be squeezed if the central bank’s benchmark rate rises.
Chairman of the National Banks Association (Perbanas), Hery Gunardi, said an increase in Bank Indonesia’s (BI) benchmark rate, known as the BI Rate, would lead to higher deposit rates. However, the extent of that increase would depend on each bank’s funding structure.
“As I have said before, when interest rates are high, only deposit pricing goes up. Deposits depend on each individual bank, because their funding structures differ,” Hery explained when met at the BRI Complex on Tuesday (21/7/2026).
The President Director of PT Bank Rakyat Indonesia (Persero) Tbk. (BBRI) confirmed that at the bank he leads, cheap funds (CASA), namely current accounts and savings, dominate the funding structure. Hery said cheap funds are unaffected by rises in the benchmark rate.
“At BRI, for instance, savings are very large, as are current accounts. And current accounts and savings do not rise with the rate. What rises are time deposits, which are indeed sensitive to pricing,” he said.
Nevertheless, Hery acknowledged that funding costs, or the cost of funds, would increase due to high interest rates. In response to this situation, he said banks cannot immediately raise their lending rates, as there is a transmission period between the benchmark rate and lending rates.
“So there will certainly be an increase in the cost of funds. But this rise in the cost of funds cannot be transmitted straight into our loan prices. If the rate rises today, lending rates do not follow immediately. There is perhaps a lag time of three to four months,” Hery explained.
When asked whether there was an interest rate war, Hery replied briefly that this was occurring in bank deposits.
As is widely known, the BI Rate has been raised by 100 basis points (bps) over the course of this year. The BI Rate currently stands at 5.75%. Tomorrow, the decision on the BI Rate will be announced at Bank Indonesia’s Board of Governors Meeting (RDG).
Looking at data from the Financial Services Authority (OJK), profitability ratios across all banking groups have indeed been eroded throughout this year.
The net interest margin (NIM) of KBMI I banks stood at 4.70% at the end of 2025, dipped to 4.56% in February, but returned to 4.70% in May 2026.
KBMI II banks recorded a NIM of 4.84% in May 2026, down from 5.11% at the end of last year. Middle-tier banks, or KBMI III, also recorded a decline to 3.77% in May 2026, from 3.91% at the end of last year.
Not to be left out, Indonesia’s big banks, or KBMI IV banks, recorded a NIM of 4.78% as of May 2026. At the end of last year, the NIM of the country’s jumbo banking group stood at 5.08%.
Source: jawawa.id (https://jawawa.id/newsitem/perbanas-chief-speaks-candidly-on-impact-to-banks-if-bi-rate-rises-1784634756)
Originally published by CNBC Indonesia (https://www.cnbcindonesia.com/market/20260721170832-17-752674/bos-perbanas-blak-blakan-soal-dampak-ke-bank-jika-bi-rate-naik), translated from Indonesian