
OJK Head Frankly Discusses Impact of US-Iran War on Banks in Indonesia
Jakarta, CNBC Indonesia — The Financial Services Authority (OJK) has revealed several risks to Indonesia’s banking industry due to the escalation of the war between the United States (US)-Israel and Iran. These geopolitical challenges, if prolonged, could create obstacles, particularly for banking intermediation functions.
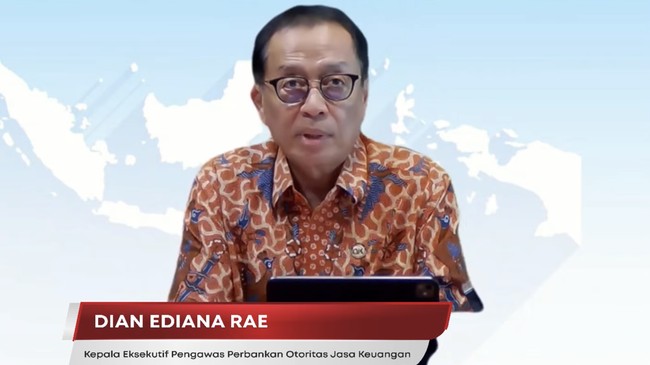
Nevertheless, Dian Ediana Rae, the Executive Head of Banking Supervision at OJK, assessed that the direct impact of the US-Israel and Iran war on Indonesia’s banking sector remains relatively limited at present.
“Considering that if we look at the direct exposure of banks to non-residents in the Middle East, it is actually quite small, both in terms of claims and liabilities, so the influence is not significant on banking capital or liquidity,” said Dian during the OJK RDK press conference on Monday (6/4/2026).
That said, Dian highlighted that the current open economy system makes Indonesia’s economy highly influenced by global situations and uncertainties. Thus, conditions in West Asia could have a significant impact on global geopolitics and geo-economics.
If the conflict drags on, it will become a source of vulnerability and also affect Indonesia’s economy, both through trade channels and financial channels.
Dian explained that the current disruption to global energy distribution routes due to the closure of the Strait of Hormuz as the main route could disturb energy commodity prices. A rise in global energy prices would then drive up fuel prices and goods distribution costs, as well as raw materials and food, which would increase pressure on global and domestic inflation.
“If this inflation pressure is responded to with tighter monetary policy, economic growth could be affected, resulting in reduced consumer spending and production activity,” said Dian.
She continued that the added cost-of-living pressures amid slowing demand would squeeze corporate margins or profits. This would increase overall business risks for companies.
This situation could be exacerbated by rising global uncertainty that prompts investors to adopt a “risk-off” stance.
“Thus, there would be an increase in Indonesia’s risk premium, followed by capital outflows and pressure on rupiah depreciation. These developments could create risks for Indonesian banking, particularly financial risks,” Dian stressed.
The impact on banking would be felt in credit risk. That is, rising energy prices and inflation pressure could increase production and distribution costs for business sectors, lowering company profitability and debtors’ ability to pay, as well as public purchasing power.
“This certainly has the potential to increase the possibility of rising problematic loans or NPLs, as well as the need for provisioning or loan loss reserves,” added Dian.
Not only that, such risks could rise in sectors sensitive to energy prices and logistics costs, such as transportation, manufacturing, and sectors dependent on imported raw materials. Furthermore, pressure on purchasing power could also increase credit risks in the MSME and consumer segments, which are more sensitive to economic changes.
Therefore, Dian said the banking industry would tend to be cautious in extending credit, which could affect future credit growth rates.
“However, amid these various risks stemming from global dynamics, Indonesia’s banking resilience is actually very strong. In fact, our financial standards, compared to the international best practices issued by the BCBS, are far above those standards,” she explained.
She detailed that in February 2026, banking capitalisation remained strong, with the industry capital adequacy ratio (CAR) at 25.83%. Meanwhile, credit quality stayed maintained with the gross non-performing loan (NPL) ratio at 2.17% and net NPL at 0.83%.
Dian continued that industry liquidity in February 2026 was also adequate, with the Liquid Assets/Non-Core Deposit (AL/NCD) ratio and Liquid Assets/Third-Party Funds (AL/DPK) at 121.29% and 27.4% respectively, well above their thresholds of 50% and 10%. The loan-to-deposit ratio (LDR) stood at 84.72%, remaining within the 78%-92% range, and the liquidity coverage ratio (LCR) was at 195.64%.