
Non-Mining Issuers Aggressively Acquire Coal Companies: What Are the Prospects?
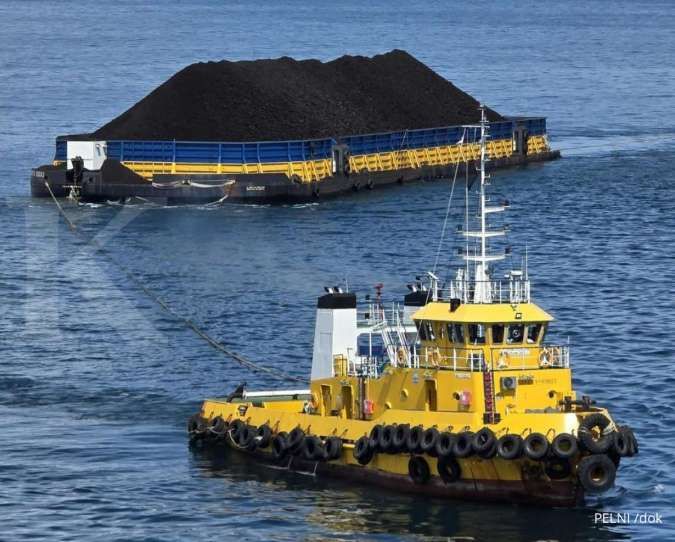
Although often described as entering its twilight years, the coal mining industry continues to hold strong appeal for a number of listed companies. This is evident from the expansion trend of several non-mining issuers into the sector.
One example is PT Singaraja Putra Tbk (SINI), which recently acquired shares in PT Kemilau Mulia Sakti (KMS), a subsidiary of PT Petrosea Tbk (PTRO), worth Rp 1.73 trillion.
Along with the acquisition, SINI is targeting consolidated coal sales volumes to rise gradually compared with the 2025 realisation of 203,057 tonnes.
Going forward, KMS, which holds coal mining assets in East Kalimantan, is targeted to gradually increase its production, starting from around 1 million tonnes per year in the initial phase to an optimal capacity of about 5 million tonnes per year.
The bulk of the funds, or Rp 20.82 trillion, will be used by FORU to acquire 49% of shares in PT Borneo Prima through an inbreng mechanism — a capital contribution in a form other than cash.
This acquisition will change FORU’s core business from media, advertising and printing into a coal mining holding company.
PT Harta Djaya Karya Tbk (MEJA) is also preparing to acquire 45% of shares in PT Trimitra Coal Perkasa (TCP) in a transaction worth around US$100 million. The acquisition is targeted for completion in the third quarter of 2026 via a share swap scheme.
To support the plan, MEJA is structuring a rights issue at a price range of Rp 450–Rp 550 per share.
Muhammad Wafi, Head of Research at Korea Investment & Sekuritas Indonesia (KISI), said several factors make the coal sector highly attractive, prompting issuers without a mining background to expand into it.
In addition, mining asset valuations are pressured by a sustainability discount even as the real cash flows of those assets remain strong.
Funding acquisitions through rights issues is also seen as cheaper for issuers given Bank Indonesia’s (BI) benchmark interest rate of 5.75%.
“The coal sector remains promising in the medium term, or 3–5 years, as long as the energy transition progresses more slowly than expected,” he said on Monday (27/7).
Key risks issuers must watch include a lack of operational experience, potential delays in Work Plan and Budget (RKAB) revisions, royalty tariff policy changes, and shifts in ESG direction that could restrict access to international funding.
Wafi believes the availability of operational mining human resources is the biggest bottleneck for issuers newly expanding into the coal sector.
Separately, Nafan Aji Gusta, Senior Market Analyst at Mirae Asset Sekuritas, said the coal sector still offers relatively strong cash flows, especially for mines with low production costs.
Moreover, domestic coal demand is still supported by power generation needs, while export demand, particularly from several Asian countries, remains fairly solid although its growth rate is starting to slow.
For metallurgical coal, the outlook is also attractive because it is used in the steel industry, giving it different demand dynamics compared with thermal coal. These factors are driving issuers to flock to the coal sector.
Furthermore, expanding through mining asset acquisitions can be a faster route than building projects from scratch.
“Issuers can immediately obtain reserves, business licences and ongoing production, potentially accelerating contributions to revenue and profit,” he said on Wednesday (28/7).
However, for issuers from different sectors, there are execution risks because the characteristics of the mining industry differ greatly from their previous businesses.