
Nine Sentiments Set to Weigh on Indonesia This Week: Super Wednesday and IMF Meeting
Jakarta, CNBC Indonesia — Indonesian financial markets ended last week on a positive note. Share prices and the rupiah strengthened, despite concerns about rising government bond yields.
Indonesia’s financial markets are expected to face considerable pressure this week amid a raft of global economic data and an important meeting in Thailand. The full outlook for today’s financial markets can be read on page three of this article.
The Jakarta Composite Index (JCI) rose 1.04% to 6,093.76 in the final trading session of last week, Friday (9 October 2026), after briefly falling below the psychological 6,000 mark. For the week, the JCI gained 0.94%.
The rise was supported by the industrial sector, up 2.1%, followed by basic materials, which gained 1.7%, and non-primary consumer goods, up 1%.
A total of 381 shares rose, 238 fell and 172 were unchanged.
Among the gainers, shares in PT Anugerah Kagum Karya Utama Tbk (AKKU) led the market last week, surging 102.50% to Rp81.
Shares in PT Asuransi Maximus Graha Persada Tbk (ASMI) followed, rising 85.71% to Rp39, while PT Lovina Beach Brewery Tbk (STRK) jumped 59.62% to Rp83.
At the other end of the market, PT ERA Merida Sejahtera Tbk (DOOH) recorded the steepest decline, plunging 26.23% to Rp270. PT Inter Delta Tbk (INTD) fell 22.68% to Rp300, while PT Perintis Triniti Properti Tbk (TRIN) dropped 21.54% to Rp204.
In currency trading, the rupiah strengthened against the US dollar at the close on Friday (9 October 2026), after weakening in the previous session.
For the week, however, the rupiah was still down 0.04%.
In the bond market, the yield on 10-year Indonesian government bonds (SBN) climbed to 7.237% on Friday, its highest level since 7 August 2026.
The increase in yields indicates that SBN prices are falling as investors sell the bonds.
US share markets closed higher on Friday (9 October 2026), supported by technology stocks after trading was unsettled by a surge in US Treasury yields, oil prices and a correction in artificial-intelligence-related shares.
The Nasdaq Composite rose 0.64% to 27,366.17, the S&P 500 gained 0.59% to 7,811.54, and the Dow Jones Industrial Average advanced 423.31 points, or 0.83%, to 51,654.95.
The gains came after US President Donald Trump said Russian President Vladimir Putin had agreed to supply diesel to the US and global markets.
Technology stocks led the advance, with Microsoft up 2% and Amazon gaining 3%. Cybersecurity company Palo Alto Networks surged 5%.
Oil prices nevertheless remained high. West Texas Intermediate crude closed at around US$92 a barrel, while Brent remained above US$104.
All three major US indices also rose over the week. The Nasdaq gained 0.6%, the Dow Jones added 0.9% and the S&P 500 advanced about 1.2%, despite long-term Treasury yields climbing to their highest level in 24 years.
Investors are now anticipating a busier earnings season next week, including results from several major US banks. The Middle East conflict and its impact on oil prices remain risks for share markets.
Global and Indonesian financial markets are expected to be influenced this week by several important events and economic data releases from China and the US.
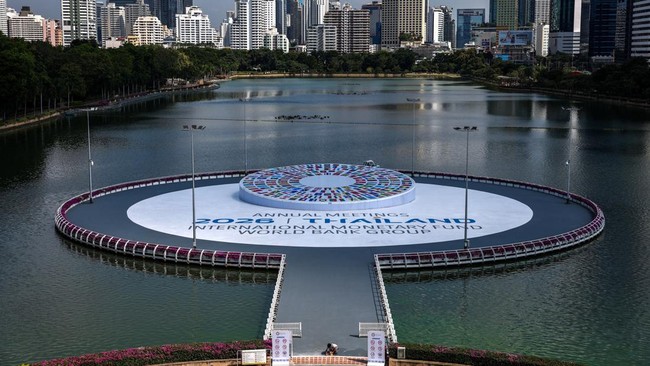
The IMF and World Bank meetings in Bangkok, Thailand, are among the key events. A number of senior officials will attend and deliver speeches, including Federal Reserve Chair Kevin Warsh.
Wednesday will be particularly important, with US and Chinese inflation data and China’s trade balance due.
Domestic developments are relatively quiet, although political tensions could rise ahead of the second anniversary of the Prabowo–Gibran administration.
The following are some of the key factors to watch today and over the coming week:
1. War developments: Trump considers helping Saudi Arabia attack the Houthis as Iran conflict widens
US President Donald Trump is considering helping Saudi Arabia attack Yemen’s Houthi group following a deadly attack at Riyadh airport. Such a move could draw the US into a new front in the war involving Iran.
“We might do it. We’ll consider it,” Trump told reporters at the White House on Saturday (10 October 2026), according to Reuters.
Two Saudi government officials said Riyadh had requested emergency defensive support from the US to help the Saudi-led coalition fight the Iran-backed Houthis.
Saudi aviation authorities said an attack on King Khalid International Airport killed 12 people and injured 309. The Houthis also renewed warnings to airlines and passengers against using Saudi airports and airspace.
The attack has heightened tensions in the region. The Houthis have also threatened oil shipping routes through the Bab el-Mandeb Strait, while Iran has effectively disrupted energy traffic through the Strait of Hormuz.
Disruptions to both strategic routes could worsen pressure on global energy supplies and keep oil prices high.
US military involvement also risks widening the conflict. The UK said it was considering additional support for Saudi Arabia, but stressed that it would not take part in offensive operations.
2. IMF and World Bank meetings (12–18 October)
Global financial officials will gather in Bangkok, Thailand, for the annual meetings of the IMF and World Bank. The event is taking place amid geopolitical turmoil, surging energy costs, rising interest rates and mounting public debt.
Under the theme “Thailand’s New Horizons: Empowering People, Building Resilience”, discussions will cover the global economic outlook, financial stability, poverty reduction, job creation and the role of private investment in development.
The US-Israeli war against Iran, now in its eighth month, and its impact on inflation will be a central focus of the annual IMF and World Bank meetings. This is the first time in three years that the meetings have been held outside Washington.
IMF Managing Director Kristalina Georgieva said about 18,000 people had registered to attend. World Bank President Ajay Banga warned that economic pressures were rising again because of higher diesel and fertiliser prices and the threat of an extreme El Niño weather event.
The IMF forecasts global growth of 3% in 2026, although some countries affected by the war risk having their growth forecasts downgraded. It has also warned that global public debt is at its highest level since the Second World War and is expected to exceed 100% of gross domestic product (GDP) before 2030.
3. China inflation (Wednesday, 14 October)
China will release its September 2026 consumer price index (CPI) and producer price index (PPI).
In August, Chinese consumer inflation was 0.8% year on year, up from 0.5% in July. Producer inflation rose to 3.8% from 3.5%.
The latest data will offer clues about the strength of domestic demand and cost pressures in the world’s second-largest economy. Developments matter to Indonesia because China is a major trading partner and an important market for Indonesian commodity exports.
4. China trade balance (Wednesday, 14 October)
China will also announce its September 2026 trade figures. In August, the country recorded a trade surplus of US$119.09 billion.
Exports surged 25% year on year to US$401.44 billion, while imports grew 28.2% to US$282.36 billion.
Investors will be watching to see whether trade growth continues. A rise in Chinese imports could benefit Indonesian exports, particularly if demand for commodities strengthens again.
5. US inflation (Wednesday, 14 October)
The US September inflation report is one of the week’s most anticipated releases. It could provide clues about the Federal Reserve’s interest-rate policy.
In August, annual US inflation remained at 3.4%, while monthly inflation rose 0.4%, driven mainly by petrol prices.
If price pressures increase again, the Fed may have less scope to ease monetary policy. The effects could spread to the US dollar, bond yields, the rupiah and emerging-market share markets.
6. Indonesia’s external debt (Thursday, 15 October)
Bank Indonesia (BI) is scheduled to release Indonesia’s External Debt Statistics for August 2026.
In July, Indonesia’s external debt stood at US$454.8 billion. Government external debt amounted to US$218.4 billion, while private-sector external debt was US$194.5 billion.
The latest figures will be watched for signs of how Indonesia’s external liabilities are evolving amid high global interest rates and exchange-rate pressure.
7. US producer inflation (Thursday, 15 October)
The US will release its September 2026 producer price index (PPI). Annual producer inflation rose to 5.4% in August, from 4.8% in July.
Higher production and transport costs are a concern because they can be passed on to consumers. If producer-level price pressures persist, bringing US inflation down could become more challenging.
8. Federal Reserve officials’ speeches (14–16 October)
Statements from Fed officials will also be in focus. Michelle W. Bowman, the Fed’s Vice Chair for Supervision, is scheduled to attend an event in Bangkok on 14 October.
The following day, Fed Chair Kevin Warsh is scheduled to speak with IMF Managing Director Kristalina Georgieva.
Key Fed events in October 2026 include:
14 October: Discussion and remarks by Michelle W. Bowman, and publication of the Beige Book.
15 October: Kevin Warsh in discussion with IMF Managing Director Kristalina Georgieva at the IMF meeting in Bangkok.
16 October: Publication of industrial production and capacity utilisation data.
The events will be closely watched for indications of Fed officials’ views on the US economy and the future direction of monetary policy.
9. US unemployment claims
The US will release unemployment claims data for the week ending 10 October 2026.
For comparison, the number of Americans filing initial claims for unemployment benefits fell by 2,000 to 197,000 in the week ending 3 October 2026. That was below the market forecast of 200,000 and the lowest since mid-July, when claims stood at 189,000.
Continuing claims, meanwhile, rose by 17,000 to 1.716 million. Despite the increase, the figure remained close to the more than three-year low recorded the previous week.
The data indicate that the US labour market remains relatively strong, in line with the Federal Reserve’s view that employment conditions remain supportive.
Today’s economic agenda:
2026 Inflation Control Coordination Meeting, alongside the signing of a joint circular by the ministers of agriculture and home affairs on the management of facilities, infrastructure and agricultural extension staff in support of sustainable food self-sufficiency. The event will take place at Sasana Bhakti Praja, at the Ministry of Home Affairs headquarters in Central Jakarta.
Launch of the Task Force for Combating the Export of Lobster Seeds (Satgas P2BBL), at the Mina Bahari Building ballroom, Ministry of Marine Affairs and Fisheries, Central Jakarta.
Digital Infrastructure Summit 2026 at Thamrin Nine Ballroom, Central Jakarta, attended by the Coordinating Minister for Infrastructure, the Deputy Minister of Communication and Digital Affairs, and the Minister of Creative Economy.
Handover ceremony and press statement by the Foreign Minister at Ruang Palapa, Ministry of Foreign Affairs, Central Jakarta.
Today’s corporate agenda:
General meeting of shareholders of PT XLSMART Telecom Sejahtera Tbk.
Payment information for the ninth coupon of series BVIC03CN2.
Interim cash dividend record date for Golden Energy Mines Tbk.
Rights issue record dates for Asuransi Harta Aman Pratama Tbk and Berlina Tbk.
Ex-dividend date for the interim cash dividend of PT Teladan Prima Agro Tbk.
Ex-dividend date for the interim cash dividend of Astra International Tbk.
Interim cash dividend record date for Astra Agro Lestari Tbk.
Ex-dividend date for the interim cash dividend of Astra International Tbk.
Listing date for the rights issue of PT VKTR Teknologi Mobilitas Tbk.
Start of trading in the rights issue of PT VKTR Teknologi Mobilitas Tbk.
The latest economic indicators are as follows:
Source: jawawa.id (https://jawawa.id/newsitem/nine-sentiments-set-to-weigh-on-indonesia-this-week-super-wednesday-and-imf-meeting-1791762701)
Originally published by CNBC Indonesia (https://www.cnbcindonesia.com/research/20261011174157-128-775124/9-sentimen-bayangi-ri-pekan-ini-super-wednesday--pertemuan-imf), translated from Indonesian