MP Supports Forensic Audit of Hajj Funds to Ensure Accountability
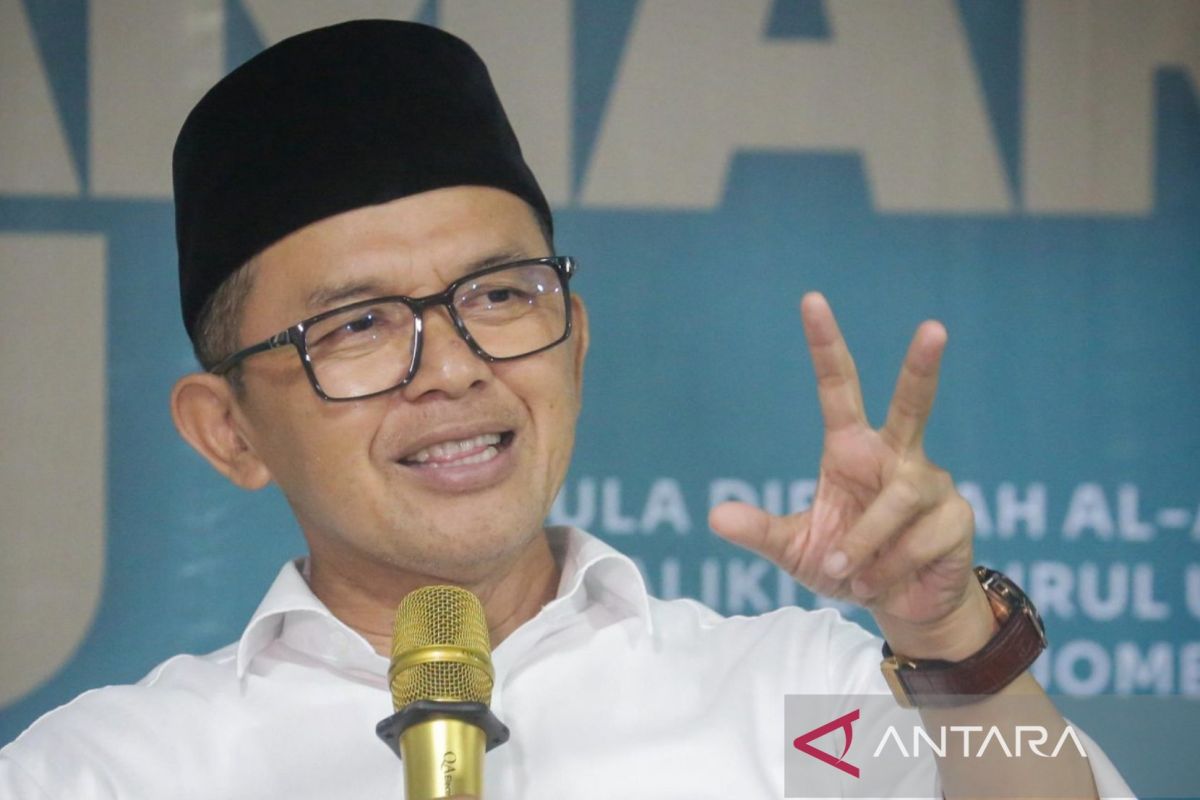
A member of Commission VIII of the Indonesian House of Responsibility (DPR RI), Maman Imanulhaq, has voiced support for the plan to conduct a forensic audit of Hajj financial management. The objective is to ensure that the funds managed on behalf of millions of pilgrims are transparent, accountable, compliant with Sharia principles, and sustainable.
“I support the forensic audit of Hajj finances, not because I assume violations have occurred, but because Hajj funds are a public trust of immense value that affects the long-term interests of the community,” Maman stated in Jakarta on Thursday.
According to him, a forensic audit should not be perceived as prejudice or an accusation against the Hajj Financial Management Agency (BPKH), but rather as a supervisory mechanism to bolster public confidence.
He noted that the BPKH’s readiness to disclose data and documents for inspection purposes is a step that deserves appreciation.
“Openness to inspection is a vital part of public institution governance. In fact, institutions with strong governance systems should not be allergic to audits,” he said.
Maman believes that a forensic audit and an Unqualified Opinion (WTP) do not need to be seen as contradictory. The BPKH previously reported that its 2025 financial statements received an Unqualified Opinion for the eighth consecutive time.
“WTP is an important achievement and must be respected, but WTP does not mean that other avenues of inspection should be closed. Similarly, a forensic audit should not be assumed from the outset to be evidence of irregularities,” Maman added.
He suggested that both mechanisms can serve as part of the checks and balances system in Hajj financial management.
“An audit is a process to discover and test facts, not a process to create conclusions before the facts have been examined,” he said.
Maman urged that the forensic audit should not only examine the figures in the financial reports but also test the integrity of the data and the transaction chain of Hajj finances from upstream to downstream.
He stated that data regarding Hajj, portion numbers, initial deposits, final payments, benefit values in virtual accounts, quotas, departure status, cancellations, refunds, and pilgrim departure data must be reconciled with BPKH records, Hajj cost data, bank accounts, and actual departures.
“What must be tested is the data chain and the transaction chain from upstream to downstream. We must ensure there are no duplicate data, discrepancies, or unauthorised changes to data,” he said.
Maman concluded that the integrity of Hajj financial management is determined not only by the final figures in financial reports but also by the validity of the entire process that produces those figures.