
MedcoEnergi Records Solid Performance in First Half of 2026
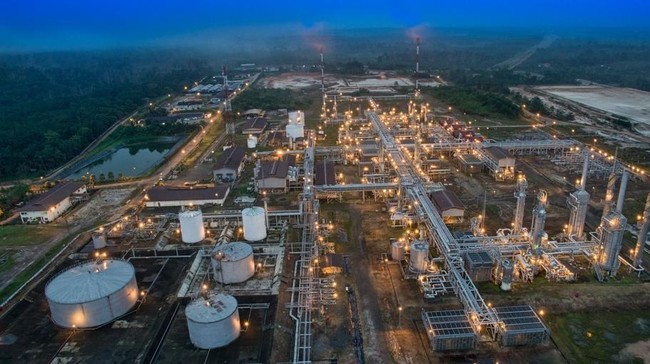
PT Medco Energi Internasional Tbk (MEDC) announced its audited financial report for the first half of 2026 on Tuesday, 22 September 2026. During this period, MedcoEnergi achieved solid performance, with oil and gas production reaching 170,000 barrels of oil equivalent per day (mboepd), in line with its 2026 guidance, with gas accounting for approximately 72% of total production.
This achievement was supported by the performance of the Company’s oil and gas blocks, including production volumes from the Corridor Block following additional participation rights, production performance at the Forel and Terubuk fields in the South Natuna Sea Block B, development drilling at the Bualuang field in Thailand, the completion of the Bisat C project in Oman Block 60, and full production contributions from the Senoro Phase 2A project.
Ronald Gunawan, CEO of MedcoEnergi, stated that the first-half results reflect the Company’s reliability in project execution and production operations management. “Our focus throughout this semester has been to ensure that key assets operate optimally and development projects proceed according to schedule. Senoro Phase 2A has been fully operational since June, and Sakakemrag remains on track for first gas in the third quarter of 2027. This is our foundation for future growth,” said Ronald. During this semester, the Company also signed Production Sharing Contracts (PSC) for the Nawasena Block in East Java and the Cendramas Block in Malaysia, where the Company was appointed as the operator, marking its first production operations in Malaysia.
The electricity segment recorded electricity sales of 2,323 GWh, higher than the same period last year, supported by the operational reliability of Dalle Energy Batam (DEB), the expansion of Energi Listrik Batam (ELB), and operations at the East Bali solar power plant. Renewable energy contributed approximately 25% of total electricity sales, aligning with the Company’s energy transition strategy. Meanwhile, copper and gold mining investments in PT Amman Mineral Internasional provided a positive contribution as the smelter reached full capacity.
Financially, MedcoEnergi booked revenue of US$1,415 million, EBITDA of US$805 million, and gross profit of US$588 million. Oil and gas production cash costs were maintained at US$8.4 per barrel of oil equivalent, below this year’s guidance. Net profit for the first half attributable to the owners of the parent entity was recorded at US$275 million, an improvement from the same period last year due to increased oil and gas production, improved global oil prices, and contributions from Amman Mineral following full smelter operations. The consolidated debt position at the end of June was recorded at US$4,128 million with cash and cash equivalents of US$1,402 million, while the net debt to EBITDA ratio for the Restricted Group was recorded at 1.4x, below the guidance of 2.5x at a mid-cycle price of US$65 per barrel. The idAA- credit rating from Pefindo, as well as international ratings from Fitch, S&P, and Moody’s, were maintained.
MedcoEnergi is maintaining its 2026 performance guidance with an oil and gas production target of 165-170 mboepd and electricity sales of 4,550 GWh, while keeping oil and gas production cash costs below US$10 per barrel of oil equivalent. In line with the Company’s commitment to investing in value-added growth opportunities, the Company has raised its 2026 capital expenditure guidance to US$450-475 million for the Oil & Gas segment, and up to US$50 million for the Electricity segment.