
Market volatility could disrupt investment, industry association warns
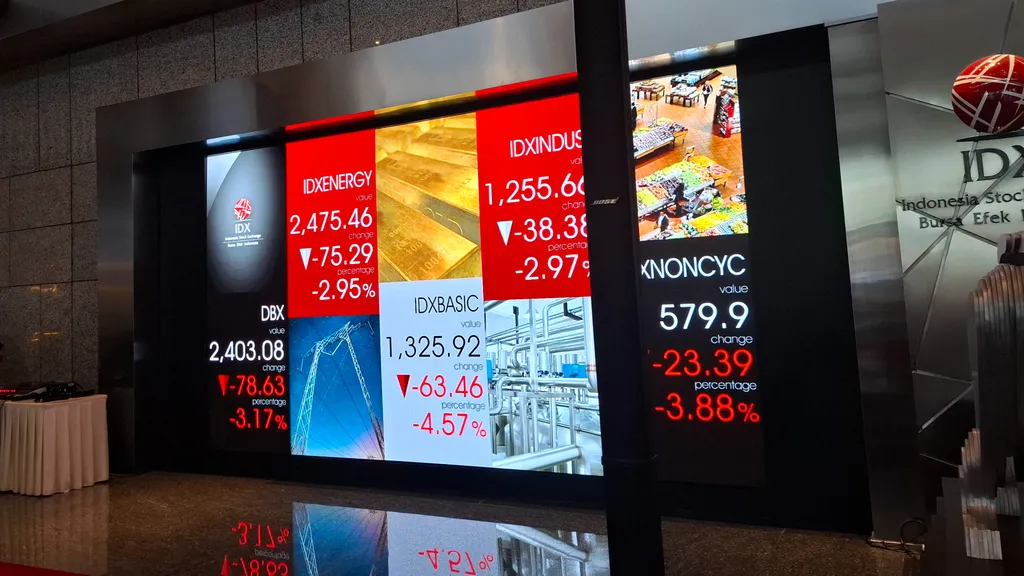
The risk that needs to be watched out for is not the sudden cessation of investment but rather the postponement of investment decisions.
19 Okt 2026 19:34 WIB · Ekonomi & Bisnis
FAKHRONAA AZIIZAH UNTUK KOMPAS
JAKARTA, KOMPAS — The turmoil in the capital market and the increasing perception of investment risk in Indonesia have the potential to delay the expansion of the manufacturing industry, particularly projects that are still in the investment decision stage.
If the pressure on the financial market continues, the increase in financing costs and the weakening of the rupiah may add to the investment burden for factory construction, machinery purchases, and industrial working capital.
The Vice Chairman of the Indonesian Industrial Estate Association (HKI), Didik Prasetiyono, on Monday (19/10/2026), stated that fluctuations in the capital market cannot be directly interpreted as a cancellation of direct investment.
Until now, there is no sufficiently strong aggregate database available to measure the investment value of tenants in industrial areas that have been specifically postponed or renegotiated due to issues related to Morgan Stanley Capital International (MSCI).
“From an industrial estate perspective, this situation is serious. However, it’s not accurate to immediately conclude that manufacturing investment has stopped or that tenants are canceling expansions en masse,” said Didik.
The risk that needs to be watched out for is not a sudden stop in investment (sudden stop), but rather a delay in investment decisions (decision delay).
Investors who have already initiated projects tend to continue their investments, while investors who have not reached a final decision may wait until market conditions, exchange rates, and financing costs are more certain.
“In the industrial zone business, a delay of six months to one year already has consequences. Land purchases are postponed, factory construction is delayed, electricity and utility needs are shifted, labor absorption is late, and downstream investments are also held back,” said Didik.
Based on data from the Ministry of Investment and Downstreaming/Investment Coordinating Board, the realization of investment in the first semester of 2026 reached Rp 1,010.6 trillion, growing by 7.2 percent compared to the same period last year.
The value is equivalent to 49.5 percent of the national investment target for 2026, which is Rp 2,041.3 trillion. Foreign direct investment (FDI) reached Rp 507.6 trillion or 50.2 percent of the total realization, while downstream investment amounted to Rp 300.1 trillion.
However, Didik reminded that the data reflects the situation up to June 2026, prior to the financial market turmoil in October. Therefore, the developments that need to be observed are their impacts on investment plans for the fourth quarter of 2026 and 2027.
Financial market pressures, Didik continued, have the potential to impact investment by increasing the cost of capital. If the country risk premium increases and government bond yields rise, corporate financing costs could also be pushed up.
Companies that issue bonds need to offer higher yields, while banks can take into account the increase in funding costs and risks when determining interest rates on loans.
The impact is particularly sensitive for industries that require large capital expenditures and long-term financing, such as factory construction, data centers, mineral smelting facilities (smelters), and the petrochemical industry.
The depreciation of the rupiah also increases the costs of procuring imported machinery and the working capital needs for industries that still rely on raw materials and intermediate goods from abroad.
“The effects can be multi-layered, such as rising risk premiums, rising financing interest rates, a weakening rupiah, and higher costs for imported machinery. Ultimately, the hurdle rate (minimum rate of return required by investors) increases, and investments previously deemed viable may be required to be revalued,” Didik said.
These concerns intensified after MSCI announced a consultation on October 15, 2026, regarding the proposed reclassification of Indonesia from an emerging market to a standalone market. Based on the announcement, Indonesia remains an emerging market, with a final decision on the proposed reclassification scheduled for the end of June 2027.
Didik assessed that if the reclassification were to actually occur, the impact could be widespread because Indonesian stocks have the potential to be removed from global indices that serve as benchmarks for various international investment funds. He referred to an estimate by Goldman Sachs, which predicts a potential outflow of passive funds amounting to approximately 5.6 billion US dollars.
According to him, the more fundamental issue is not merely the decline in the Composite Stock Price Index (IHSG), but rather the possibility that such volatility increases the risk premium and the cost of capital in Indonesia structurally.
This condition can reduce the feasibility of manufacturing projects and affect Indonesia’s competitiveness in competing for global investment.
Didik added that international investors compare Indonesia with competing countries, such as Vietnam, Malaysia, Thailand, and India, when determining the location for the construction of production facilities. In addition to land prices, electricity, gas, logistics, and regulatory certainty, investors also take into account exchange rates, the availability of clean energy, and financing costs.
“Financial market turbulence needs to be anticipated to prevent it from developing into a trust issue regarding the Indonesian economy as a whole. The capital market and direct investment are indeed two different channels, but both are equally influenced by investors’ perceptions of risk and business certainty.”
Improving governance
To maintain investment attractiveness, Didik urged the government to improve the credibility of financial markets while strengthening the competitiveness of the real sector. Capital market reform, he said, needs to be directed at transparency in share ownership structures, transparency regarding beneficial owners, the quality of publicly traded shares (free float), and enforcement of regulations against alleged trade violations.
The Indonesian capital market authority has announced several improvements, including increased transparency of share ownership data and an increase in the minimum free float to 15 percent. However, Didik believes that global investors are not sufficiently reassured by the announcement of regulatory changes. They need evidence that the rules are consistently applied and produce verifiable improvements.
“The international market cannot be sufficiently convinced by announcements. They look for enforcement, consistency, and results. If violations have been found, the sanctions must be swift, transparent, proportional, and have a deterrent effect,” he stated.
In the real sector, the government also needs to ensure that the cost of doing business in Indonesia does not continue to rise. This can be achieved through price and supply certainty of electricity and gas, acceleration of licensing, land tenure certainty, logistics efficiency, strengthening of fiscal incentives, and expanding access to long-term investment financing.
According to Didik, the realization of investments in the first semester of 2026, which continues to grow, indicates that Indonesia has a sufficiently strong investment base. However, this advantage needs to be accompanied by policy certainty and improvements in governance so that investors continue to view Indonesia as a competitive investment destination.
He believes that the momentum of the MSCI evaluation should be utilized as an impetus to improve capital market governance, rather than merely viewed as a threat to the stock index. If the government’s and authorities’ responses are conducted transparently and credibly, investor confidence can still be restored.
Conversely, if the reforms do not yield measurable changes, the pressure risks spreading from the stock market to exchange rates and bonds, subsequently increasing the cost of capital and affecting decisions regarding factory development. Ultimately, issues that originate in the financial market can become obstacles to the realization of investments and the national industrialization agenda.
The fluctuations in the stock market are considered to have no direct impact on investment decisions in the textile and textile products industry. The more fundamental issues for this labor-intensive industry are the narrowing access to financing, product competitiveness, and regulations that are still deemed burdensome for the business world.
The Chairperson of the Indonesian Garment and Textile Association (AGTI), Anne Patricia Sutanto, stated that fluctuations in the capital market do not significantly impact investment decisions in the textile and garment industry. This is because the development of the industry does not solely rely on capital increases through the stock market, but also depends on credit from financial institutions and financing from suppliers (suppliers credit).
“To develop the textile and garment industry, it is not only from equity. It can also come from suppliers’ credit, and it can also come from financial institution credit. Therefore, this indeed depends not on the capital market, but on the textile and garment market in Indonesian society and abroad,” said Anne, when contacted in Jakarta, Monday (19/10/2026).
According to Anne, the investment needs of the textile and garment industry, such as for the purchase of machinery and the development of production systems, are greatly determined by demand prospects and product competitiveness.
Therefore, stock market fluctuations are not the main issue hindering expansion. The more fundamental challenge is the industry’s ability to secure financing and create competitive advantages to compete in both domestic and export markets.
Anne stated that access to financing for the textile and garment industry tends to be narrowing. This condition complicates companies that require funding to update machinery, enhance productivity, and expand production capacity.
“Financing that is more competitive is needed. Access to financing for the textile and garment industry is not developing, but rather shrinking. So, how can we expand?” said Anne.
In addition to financing, regulatory reform to reduce the burden on the business world is an agenda that needs attention. According to Anne, government support does not necessarily have to be manifested through large fiscal incentives, but can take the form of simplifying rules that hinder investment and increase productivity. Incentives will not be effective if companies continue to face burdensome regulatory requirements.
“TPT does not need over-protection (safeguards or import quotas) as it risks provoking reciprocity from other countries, the need for benchmarking with competitor countries (such as Vietnam), and protection measures like reasonable tariffs are only temporary (around 3 years),” he said.
The issue is also related to the labor-intensive nature of the garment industry. Anne reminded that labor regulations need to balance worker protection with the necessity of maintaining competitiveness and creating job opportunities.
In addition, the government needs to ensure that imported goods comply with legal provisions, while also promoting improvements in technology, productivity, and the quality of domestic products.
Writer:
Aguido AdriEditor:
Budi Suwarna
Source: jawawa.id (https://jawawa.id/newsitem/market-volatility-could-disrupt-investment-industry-association-warns-1792417810)
Originally published by kompas.id (https://www.kompas.id/artikel/market-turmoil-has-the-potential-to-disrupt-investment?open_from=English_Page)