
JCI Takes a Hit as Indonesia Faces Standalone Market Downgrade Threat: ‘MSCI Has Gone Too Far’
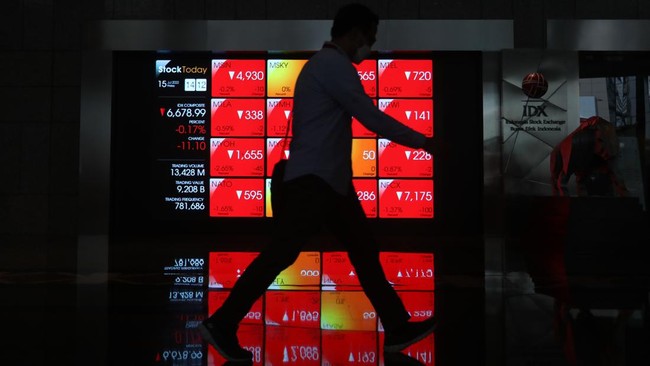
Jakarta, CNBC Indonesia — Indonesia’s stock market came under heavy pressure in trading on Friday (16 October 2026).
The Jakarta Composite Index (JCI) plunged 8% to 5,393.92 at the market open, triggering a temporary trading halt. The Indonesia Stock Exchange (IDX) suspended trading for 30 minutes before reopening at 9.28am Western Indonesia Time.
After trading resumed, the JCI continued to fall. At 10.20am it was down 10.65%, to 5,239.32.
The market rout followed an announcement by global index provider Morgan Stanley Capital International (MSCI) on Thursday (15 October 2026), US time, concerning the future classification of Indonesia’s equity market. MSCI has formally opened a consultation on a proposal to downgrade Indonesia from an emerging market to a standalone market.
The proposal is considered serious because MSCI believes the problems in Indonesia’s capital market are too significant for the country to be placed merely in the frontier market category, which ranks below emerging markets.
MSCI cited several issues that remain a concern for global investors, including insufficient transparency over share ownership, concentrated ownership, suspected coordinated share trading and a lack of convincing enforcement of rules.
Capital market authorities have announced a number of reforms, including disclosure of shareholders with stakes above 1% and plans to raise the minimum public float to 15%. However, MSCI said the measures had yet to produce consistent, tangible results across the market.
The reclassification is not yet final. MSCI’s consultation will remain open until 30 April 2027, with a final decision due no later than 30 June 2027.
Even though a final decision is still months away, Indonesia’s stock market has already come under substantial pressure. Analysts say the downgrade threat could have wider repercussions for the country’s financial markets, particularly if the concerns raised by MSCI are not addressed promptly.
Foreign outflows threaten to weigh on shares, particularly banks
Nafan Aji Gusta, an analyst at Mirae Asset Sekuritas, said downgrading Indonesia to standalone market status could have a significant impact on the domestic capital market.
Many global institutional investors use MSCI indices as benchmarks when deciding where to invest. If Indonesia loses its emerging market status, investors tracking those indices may have to adjust their portfolios, including by reducing their holdings in Indonesian shares.
“In my view, if MSCI really downgrades Indonesia from emerging market to standalone market, the impact on the domestic capital market will be significant—in terms of foreign fund flows, trading liquidity, share-price volatility and global investors’ perception of Indonesia’s investment risk,” Nafan told CNBC Indonesia on Friday (16 October 2026).
He said the greatest risk of pressure would be on large-cap shares with high foreign ownership.
“If portfolio adjustments take place all at once, selling pressure could be concentrated in large-cap shares with significant index weightings and high foreign ownership, including several major banking stocks,” he said.
Nafan added that the scale of the impact would depend on MSCI’s final decision, when it was implemented and the ability of domestic investors to absorb the selling pressure.
Beyond share-price movements, he said MSCI’s announcement was a serious warning to Indonesia’s capital market authorities.
“In my view, this is a serious warning that capital market reforms in Indonesia have so far failed to convince global institutional investors in terms of implementation and tangible results,” he said.
Nafan called on the Indonesia Stock Exchange (IDX), the Financial Services Authority (OJK), the Indonesian Central Securities Depository (KSEI) and the government to strengthen ownership transparency, market surveillance and consistent enforcement of rules.
MSCI threat could have lasting effects and spill over into the rupiah
Irman Faiz, lead economist at Bank Danamon, expressed a similar view.
In a report entitled MSCI Downgrade Threat: A Structural Equity Shock with Broader External Risks, Irman said the threat of a downgrade could put broader pressure on financial markets, including the rupiah.
The report showed that Indonesia’s weighting in MSCI’s emerging market indices had already fallen sharply. Its weight in the MSCI Emerging Markets Index declined from 1.16% in December 2025 to just 0.43% in September 2026. Over the same period, the number of shares in the MSCI Indonesia Index fell from 18 to nine.
However, the reduction in Indonesia’s index weighting does not entirely reflect share sales by foreign investors. Share-price movements, the number of shares available for trading and changes in index composition also affect the calculation.
Another concern is the large share of banking stocks in the MSCI Indonesia Index. According to Bank Danamon, the financial sector accounted for 71.7% of the index as of September 2026, comprising shares in PT Bank Central Asia Tbk (BBCA), PT Bank Rakyat Indonesia (Persero) Tbk (BBRI), PT Bank Mandiri (Persero) Tbk (BMRI) and PT Bank Negara Indonesia (Persero) Tbk (BBNI).
This could leave major bank shares vulnerable to selling if the downgrade goes ahead.
Irman said, however, that the greater risk would arise if Indonesia were excluded for an extended period from major indices used as benchmarks by global institutional investors. This could reduce foreign investor interest, thin out share trading and raise companies’ funding costs.
Pressure could also spill over into the rupiah if foreign investors chose to withdraw their funds from Indonesia.
“With Indonesia’s current account deficit projected to reach 1.5% of GDP in 2026 and 1.6% in 2027, additional proceeds from equity investments being repatriated could add to pressure on the rupiah and raise the yields required to attract foreign capital,” Irman wrote in the Bank Danamon report.
Nevertheless, Bank Danamon does not view the threat as an immediate balance-of-payments crisis. Foreign investors selling shares does not necessarily mean that the funds will immediately leave Indonesia.
The economic impact would become more pronounced if the pressure persisted, making it harder for companies to raise new funds through the stock market and increasing the cost of investment.
Against this backdrop, Irman said MSCI’s proposal to downgrade Indonesia directly from emerging market to standalone market was excessive.
“In my view, going to standalone is too much,” Irman told CNBC Indonesia on Friday (16 October 2026).
He said Indonesia’s economic fundamentals and regulatory framework remained very different from those of countries classified as standalone markets.
Nevertheless, Irman hoped MSCI’s announcement would spur Indonesia’s capital market authorities to make improvements.
“But perhaps this can be a push factor for our authorities to put things right,” he said.
Foreign investors have already lost confidence
Maximilianus Nico Demus of Pilarmas Investindo Sekuritas said MSCI’s announcement reflected a loss of foreign investor confidence in Indonesia’s financial markets, which he believed had been weakening since the beginning of the year.
“Whether it is fair or not, the market will judge,” Nico told CNBC Indonesia on Friday (16 October 2026).
He said Indonesia’s stock market had already been facing a range of challenges before MSCI’s announcement.
“From the start of the year, there has been no reason for foreign investors to enter Indonesia’s financial market,” he said.
Nico linked the situation to waning investor confidence, concerns about fiscal policy management and what he described as domestic political instability.
He said MSCI’s criteria should be respected. The key question, he argued, was whether Indonesia’s stock market could withstand the situation without substantial support from foreign investors.
“MSCI has its own criteria, which we must respect,” he said.
“The question is how much we should react to this. Can we really stand on our own two feet without the help of foreign investors, when we are only an emerging market?” Nico added.
With MSCI’s decision not expected until June 2027, Indonesia still has time to demonstrate progress. But analysts’ views suggest the challenge extends beyond a single day’s collapse in the JCI: the larger task is to restore foreign investors’ confidence and ensure Indonesia’s stock market remains attractive to global investment over the long term.
Source: jawawa.id (https://jawawa.id/newsitem/jci-takes-a-hit-as-indonesia-faces-standalone-market-downgrade-threat-msci-has-gone-too-far-1792126247)
Originally published by CNBC Indonesia (https://www.cnbcindonesia.com/research/20261016095741-128-776740/ihsg-jadi-korban-ri-terancam-masuk-standalone-market-msci-too-much), translated from Indonesian