
JCI Edges Up 0.06% at the Start of Trading
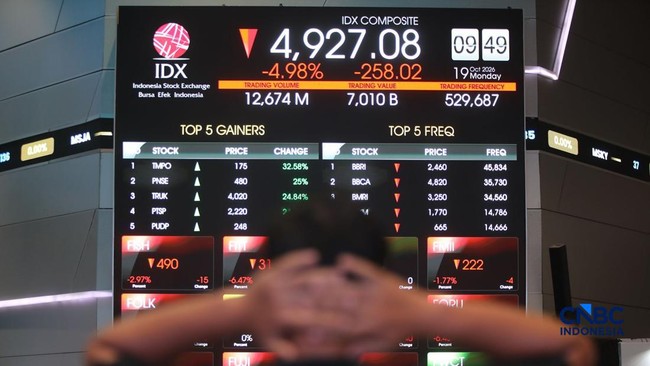
Jakarta, CNBC Indonesia — Indonesia’s Composite Stock Price Index (JCI) began the week in positive territory on Monday (26 October 2026). It opened at 5,442.30, up 3.04 points, or around 0.06%, from the previous close of 5,439.26.
Trading was relatively subdued during the morning’s first session. The JCI briefly reached a high of 5,449.35, while its low was 5,438.75.
Early-session trading volume reached 5.23 million lots, with transactions worth around Rp244.76 billion.
Global and Indonesian financial markets face a busy week. Developments in the war remain a key market driver, alongside several important events, including central-bank decisions that could move equities, bonds, foreign exchange and commodities.
Seven central banks are due to announce monetary policy decisions this week: the State Bank of Pakistan on 26 October; the US Federal Reserve, Bank of Canada, Reserve Bank of New Zealand and Bank of Thailand on 28 October; the European Central Bank (ECB) on 29 October; and the Bank of Japan (BOJ) on 30 October.
Investors will also monitor US and eurozone economic growth figures, as well as US PCE inflation, one of the key indicators the Federal Reserve uses to guide monetary policy.
Here are the main economic events markets will be watching this week.
1. Chinese Communist Party meeting
The Fifth Plenum of the Communist Party of China’s Central Committee is an important meeting to discuss the country’s political direction and strategic policies. The party will consider economic, industrial and technology policy, as well as China’s development priorities for the coming years.
Scheduled for 26–29 October 2026, the meeting is in focus for the signals it may provide on President Xi Jinping’s consolidation of power, the intensification of anti-corruption efforts and the government’s priorities ahead of 2027.
For global investors, its outcomes matter for assessing policy certainty, the business climate and China’s economic outlook, with implications for equity markets, the yuan, commodity prices and trading partners such as Indonesia.
2. China’s industrial profits in September 2026
China will release industrial profit data for January to September on Tuesday (27 October) at 08.30 WIB. Industrial profits grew 15.7% year on year in January–August, down from 17.6% in January–July. A further slowdown could weigh on the outlook for commodity demand, while stronger profits could signal a recovery in industrial activity and investment.
3. Federal Reserve rate decision for October 2026
The Federal Reserve is scheduled to announce its rate decision on Wednesday US time, or Thursday (29 October) at 01.00 WIB, followed by a press conference at 01.30 WIB.
Market consensus expects the US central bank to hold rates at 3.75%–4.00%, after raising them by 25 basis points in September.
Although rates are expected to remain unchanged, investors will focus on Fed Chair Kevin Warsh’s comments on the inflation outlook, labour-market conditions and the possibility of further tightening.
A more hawkish stance could strengthen the US dollar and weigh on risk assets, including emerging-market shares. Conversely, signals that inflationary pressures are easing could prompt markets to reassess the US monetary policy outlook.
For Indonesia, the Fed’s policy direction is an important factor affecting the rupiah, foreign capital flows and the appeal of government bonds (SBN).
4. US economic growth in the third quarter of 2026
The first estimate of US third-quarter GDP will be released on Thursday (29 October) at 19.30 WIB.
The US economy is expected to have grown by 3.2% quarter on quarter at an annualised rate, up from 2.2% in the previous quarter. Stronger growth could confirm the resilience of the US economy, but if accompanied by high inflation, it could strengthen expectations that interest rates will remain elevated for longer.
5. US PCE inflation
The US will also release September Personal Consumption Expenditures (PCE) inflation data on Thursday (29 October) at 19.30 WIB.
In August 2026, PCE inflation stood at 3.4% year on year, while core inflation was 3.0%.
Core PCE inflation, which excludes food and energy, is expected to rise by 0.3% month on month in September 2026, compared with 0.2% in August. Year on year, core inflation is forecast to increase to 3.1% from 3.0%.
The data matter because PCE is one of the main inflation indicators used by the Federal Reserve to determine monetary policy.
If inflation exceeds expectations, concerns that price pressures remain difficult to control could intensify, potentially reinforcing expectations that interest rates will stay higher for longer.
Conversely, lower inflation could ease market pressure, although a consistent decline would be needed before the monetary policy outlook changed significantly.
6. ECB rate decision for October 2026
The ECB is scheduled to announce its rate decision on Thursday (29 October) at 20.15 WIB, with a press conference at 20.45 WIB.
Consensus forecasts put the main refinancing rate at 2.65% and the deposit facility rate at 2.50%, both unchanged.
Investors will watch how the ECB balances inflation risks against slowing economic growth in Europe. Energy price pressures and uncertainty over growth will be important factors in determining the next policy steps.
7. BOJ rate decision for October 2026
The BOJ is scheduled to announce its rate decision on Friday (30 October), although the release time may vary according to the central bank’s official schedule.
Consensus expects the BOJ to hold its rate at 1.25%, after raising it from 1.00% in September.
Alongside the rate decision, markets will monitor the bank’s outlook report on the economy and prices, including any revisions to growth and inflation forecasts and its assessment of wage and consumption trends.
8. Eurozone economic growth in the third quarter of 2026
The first estimate of eurozone GDP will be released on Friday (30 October) at 17.00 WIB.
The economy is expected to grow by 0.2% quarter on quarter, slowing from 0.6% in the previous quarter.
Annual growth is forecast at 1.1%, down from 1.2%. A sharper slowdown could heighten concerns about the region’s economy and be an important consideration for the ECB’s policy direction.
Source: jawawa.id (https://jawawa.id/newsitem/jci-edges-up-0-06-at-the-start-of-trading-1792983032)
Originally published by CNBC Indonesia (https://www.cnbcindonesia.com/market/20261026085546-17-779343/awal-perdagangan-ihsg-menguat-terbatas-006), translated from Indonesian