Is Additional Foreign Loan Allocation Needed for the Defence Sector?
Anomalies seem to have become a new normal in the current government’s fiscal policy, given that such anomalies are being normalised. It is termed an anomaly because, instead of reducing spending to escape the threat of a budget deficit exceeding three per cent of GDP, the government’s fiscal policy is continuing several expenditure activities that have been criticised by various parties.
The easing of global geopolitical tensions has not reduced the pressure on the Indonesian economy, considering the factor of market distrust towards the government’s fiscal policy. The Rupiah exchange rate against the US Dollar continues to face pressure, while the market awaits the assessment of S&P Global Ratings regarding Indonesia’s government debt.
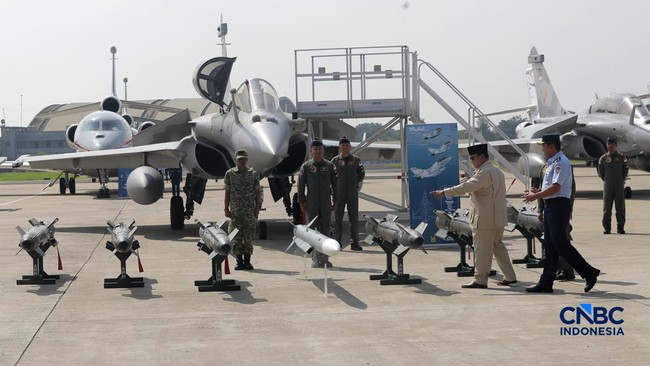
Defence spending is one of the major expenditures currently undertaken by the government, with the Pure Rupiah (RM) budget allocated to the Ministry of Defence and the State Budget Treasury Office (BUN) totalling Rp 335 trillion. Other sources of RM include Domestic Loans (PDN) worth Rp 54 trillion, which is the budget for the 2025-2029 period.
There is also Foreign Loan (PLN) allocation of US$ 34.8 billion, for which the budget has received the Determination of Funding Sources (PSP) from the Minister of Finance. Naturally, the execution of this US$ 34.8 billion PSP in the form of contract activation cannot be carried out this year, as it requires Accompanying Pure Rupiah (RMP) equivalent to US$ 5.2 billion. The simultaneous issuance of the Blue Book, Green Book, List of Special Activities, and PSP is another anomaly in the government’s current fiscal policy.
The large allocation of PLN for defence spending during the 2025-2029 period is not surprising, considering that in previous eras, the PLN quota was US$ 34.7 billion, even though it was temporarily reduced to US$ 25 billion during President Joko Widodo’s era before being increased again after President Prabowo Subianto took power.
However, the amount of PLN for the 2025-2029 period is also an anomaly because the government’s fiscal space is narrowing, with several other programmes also deemed priorities and non-negotiable. Expecting lenders to finance 100 per cent of the PLN is an impossibility, considering market distrust, the downgrade of Indonesia’s debt outlook by Moody’s and Fitch Ratings, and the possibility of a sovereign credit rating downgrade this year.
Should a global rating agency downgrade Indonesia’s government debt, it would take several years for Indonesia to restore that rating, especially if it is downgraded to non-investment grade.
As previously discussed, the effort to realise spending of US$ 3 namely 8 billion will face several challenges related to market distrust of the government’s fiscal policy. Such spending will also increase Indonesia’s debt risk, given that US$ 14 billion is planned to come from Foreign Private Creditors (KSA), which are known to have much higher interest rates than loans under the Export Credit Agency (LPKE) scheme.
Furthermore, there is a challenge regarding the availability of RMP to support the US$ 34.8 billion PSP, as fiscal space narrows and the Rupiah exchange rate against the US Dollar shows no signs of significant strengthening. Given the lack of transparency regarding the use of PLN in the defence sector, it remains a question whether the list of programmes receiving PSP is truly necessary or if they are being purchased without considering issues of effectiveness, including operational integration with other various defence equipment.
Referring to the experience of weapons system acquisitions during the second term of President Susilo Bambang Yudhoyono’s administration, although the PLN quota was only US$ 6.5 billion, Indonesia was able to bring in first-tier NATO warfare equipment such as the AH-64E, Leopard 2A4, CAESAR 155 mm, and M109A4BE. Can the current administration replicate the achievements of the 2009-2014 era, which was only equipped with a PLN of US$ 6.5 billion, with a PLN allowance of US$ 34.8 billion?
There is still doubt regarding this, due to the immaturity of the defence planning process—if not to say its absence—alongside the strong parochial interests in defence spending in recent years. As an illustration, the plan to import the F-15EX since 2020 has remained mere discourse, not because the government lacks fiscal space, but partly due to a lack of sincere intention to realise that endeavour.
The question regarding the size of the current PLN allocation is not whether the budget is sufficient to meet defence needs until the end of the decade, but whether the PLN is utilised effectively and efficiently. The issues of effectiveness and efficiency in the use of PLN do not seem to be a primary focus at present, neither in terms of debt risk management nor the position of purchased weapon systems within the broader defence framework.
While the utilisation of US$ 34.8 billion in PLN must be scrutinised for several years to come, there are reportedly aspirations for an additional PLN allocation of approximately US$ 10 billion to US$ 15 billion, which, if realised, would bring the PLN allocation until 2029 to US$ 50 billion.
Of course, if such aspirations are realised, the exposure to PLN will burden the Ministry of Defence’s budget during the 2030-2050 period, as the payment of both interest and principal of the debt comes from the ministry’s capital expenditure budget.
If these aspirations are true, are there certain defence equipment acquisition plans that cannot be accommodated by the US$ 34.8 billion PLN? Or are there planned expenditure activities that are inefficient within the Medium-Term Foreign Loan List (DRPLN)?