
Indonesia's Data Centre Business Projected to Grow Rapidly, TLKM and ISAT Seen as Top Picks
Indonesia’s data centre industry is considered to still be in the early stages of growth, despite having a large expansion pipeline. This opens opportunities for a number of listed companies to capture the growing demand for digital infrastructure in the coming years.
Equity Research Analysts at BRI Danareksa Sekuritas, Kafi Ananta and Erindra Krisnawan, stated that installed IT data centre capacity in Indonesia reached around 580 megawatts (MW) in the first half of 2026. This capacity is projected to surge to 3.5 gigawatts (GW) by 2030.
“This growth is driven by increasing demand for cloud services and AI infrastructure that requires GPUs in large quantities, while regional capacity constraints open up growth opportunities for Indonesia’s data centres,” they wrote in research released on Friday (21/8/2026).
Jakarta is recorded as having operational capacity of 322 MW and a pipeline of around 1.7 GW. Meanwhile, Batam has operational capacity of 126 MW with a pipeline reaching 1.4 GW, making both regions the main centres for national data centre development.
According to Kafi and Erindra, Jakarta is largely supported by domestic demand, while Batam has the potential to become a recipient of regional spillover from Singapore. Batam also has advantages in terms of proximity to Singapore and submarine cable connectivity.
“The Jakarta and Batam data centre markets are still in the early phase of growth, with capacity still heavily concentrated in projects within the pipeline,” they said.
They noted that industry growth is also driven by developments in cloud and artificial intelligence (AI) demand. In Batam, for example, the hyperscale segment dominates with a share of around 71%, while a number of projects are being directed towards meeting AI computing needs.
Nevertheless, the largest pipeline in Indonesia’s data centre industry is currently still dominated by private operators and players backed by foreign investors. Several operators are recorded as having pipelines of hundreds of megawatts, such as DayOne at 450 MW, Princeton Digital at 360 MW, ST Telemedia at 322 MW, and GDC and EdgeConneX at 200 MW each.
Amid the dominance of these players, a number of local listed companies are beginning to build exposure through facility development and partnerships with global operators. Kafi and Erindra assess that TLKM, ISAT, DSSA and DCII have the largest direct exposure to the sector’s growth.
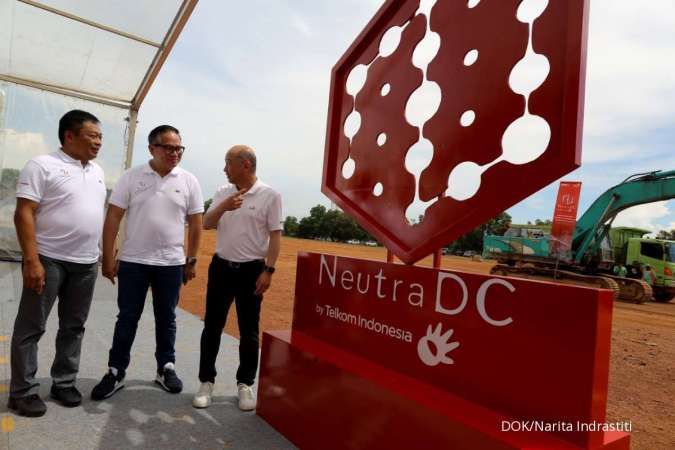
For PT Telkom Indonesia Tbk (TLKM), exposure to the data centre business comes from NeutraDC. The company already has IT capacity of 90.4 MW and is targeting total capacity of 300 MW by 2030.
Meanwhile, PT Indosat Tbk (ISAT) has exposure through a 25% stake in BDx Indonesia. BDx operates 30 MW across three edge campuses and has a 72 MW hyperscale facility at CGK4 Jatiluhur.
ISAT also has the potential to hold a 30% stake in Zankore, an AI neocloud joint venture with its parent company, Ooredoo. BRI Danareksa estimates that this ownership could provide significant potential value accretion for ISAT.
On the other hand, PT Dian Swastatika Sentosa Tbk (DSSA) operates 24 edge data centres with a total capacity of 10 MW. DSSA is also developing SMX01 in Jakarta through a joint venture with LG.
As for PT DCI Indonesia Tbk (DCII), it is the player most focused on the data centre business. DCII currently has operational capacity of 128 MW across four facilities and has a large expansion pipeline.
“DCII is the largest pure-play data centre with operational capacity of 128 MW and the deepest pipeline, especially the H3 project in Bintan which has a capacity of more than 1,000 MW,” explained Kafi and Erindra.
The H3 Sky DC Park project in Bintan is one of DCII’s largest expansion options. The project has capacity that can be developed to more than 1,000 MW on around 700 hectares of land, and is directed at capturing spillover demand from Singapore.
In addition to these four listed companies, Kafi and Erindra also highlighted a number of early-stage players such as PT NexAI Digital Infrastruktur Tbk (MGLV), PT Sinergi Inti Andalan Prima Tbk (INET), and PT Bakrie & Brothers Tbk (BNBR).
MGLV plans to transform into a data centre platform and acquire two Nextier assets with a total capacity of 96 MW. Meanwhile, INET, through its subsidiary SIDI, has developed colocation data centre facilities and plans to build a green data centre in Jatiluhur.
“Overall, we are positive on the data centre theme because its growth is structural and long-term, with power certainty and operational scale being differentiating factors,” explained Kafi and Erindra.