
Impact of Danantara Involvement, Petrochemical Issuers' Prospects Become More Convincing
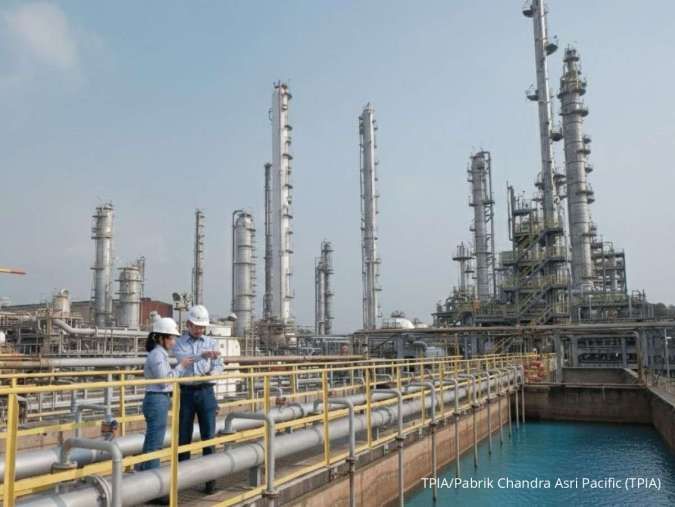
Amidst various challenges, the petrochemical sector still holds promising prospects. This is in line with BPI Danantara’s move, which appears to be positioning petrochemicals as a strategic industry for Indonesia.
Previously, Danantara, together with the Indonesia Investment Authority (INA), acted as a strategic investor in the Chlor Alkali - Ethylene Dichloride (CA-EDC) plant construction project developed by PT Chandra Asri Pacific Tbk (TPIA). Danantara and INA invested US$200 million in the plant, which is targeted to commence operations in 2027.
Recently, Lotte Chemical Corp. Ltd., a South Korean chemical company, was reported to be planning to divest part of its stake in Lotte Chemical Indonesia (LCI) to Danantara as part of its petrochemical business restructuring plan. LCI is a sister company of PT Lotte Chemical Titan Tbk (FPNI), which actively operates in the downstream petrochemical segment.
Senior Market Analyst at Mirae Asset Sekuritas, Nafan Aji Gusta, said that Danantara’s involvement is a positive signal for Indonesia’s petrochemical ecosystem in the medium and long term, as it demonstrates that the sector is viewed as strategic for strengthening the national industry and reducing dependence on imports.
For issuers such as TPIA, the presence of Danantara and INA as strategic investors can serve as a catalyst by strengthening funding, project credibility, and opening opportunities for synergy with the government. Additionally, if Danantara does indeed take ownership of LCI, FPNI could benefit from positive sentiment while improving the perception of the Lotte Chemical ecosystem in Indonesia.
“However, investors need to distinguish between sentiment based on rumours and fundamental benefits that have already been realised,” he said on Thursday (27/8/2026).
In general, petrochemical producer issuers still have the opportunity to deliver positive performance for the remainder of the year. However, the petrochemical sector cannot yet be described as fully expansive.
Challenges in this sector are also not easy, given the risk of high raw material prices amid global oil price volatility. Furthermore, Indonesia is threatened with becoming a target for dumping of processed petrochemical products, particularly from China.
In addition, government support is clearly still needed. Not only as a strategic investor, the government also needs to be present through the strengthening of Anti-Dumping Import Duty (BMAD) policies to protect local producers.
Among the various petrochemical issuers, Wafi named TPIA and PT Barito Renewables Energy Tbk (BRPT) as the top picks in this sector. Besides benefiting from the 0% LPG import duty incentive, they also receive validation of support from Danantara for the CA-EDC project and diversification into various other business sectors, including waste-to-energy processing.
“They need to secure raw material supply and accelerate the waste-to-energy (WtE) project,” he said on Thursday (27/8/2026).
Wafi also mentioned that investors can hold BRPT shares with a fair price target of Rp 1,400 per share.
On the other hand, Nafan said that the performance of petrochemical issuers in the second half of 2026 will depend heavily on margin recovery, cost control, capacity utilisation, and raw material price developments.
Nafan then recommended adding BRPT and TPIA shares with price targets of Rp 2,630 per share and Rp 2,940 per share respectively.
Source: jawawa.id (https://jawawa.id/newsitem/impact-of-danantara-involvement-petrochemical-issuers-prospects-become-more-convincing-1787885416)
Originally published by investasi.kontan.co.id (https://investasi.kontan.co.id/news/imbas-keterlibatan-danantara-prospek-emiten-petrokimia-jadi-lebih-meyakinkan), translated from Indonesian