
IDX Composite strengthens amid 'wait and see' approach to domestic and global economic data
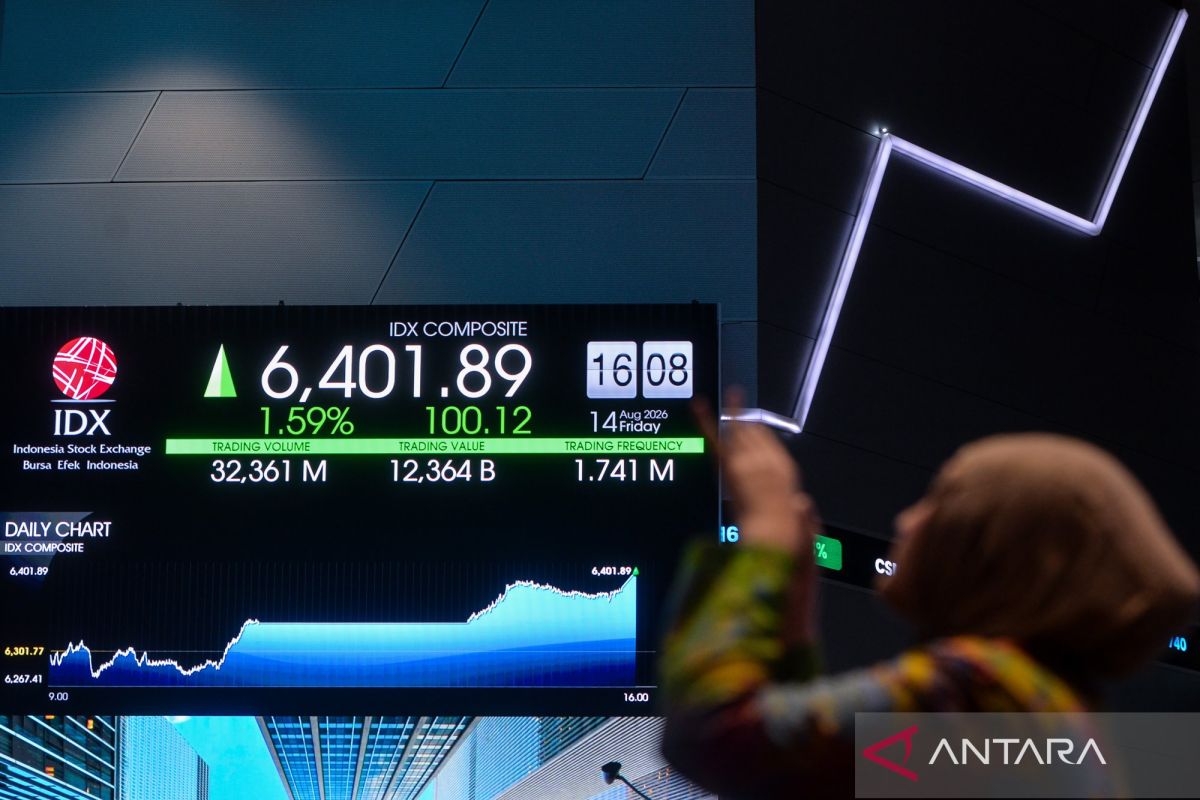
Jakarta (ANTARA) - The Indonesia Composite Index (IHSG) on the Indonesia Stock Exchange (IDX) moved higher on Tuesday morning, as market participants adopted a ‘wait and see’ approach regarding domestic and global economic data.
The IHSG opened up 12.64 points or 0.19 per cent to 6,538.12. Meanwhile, the LQ45 index, comprising 45 blue-chip stocks, rose 0.92 points or 0.14 per cent to 644.75.
“The IHSG is expected to consolidate within the 6,450-6,570 range during Tuesday’s trading,” said Ratna Lim, Head of Research at Phintraco Sekuritas, in her analysis in Jakarta on Tuesday.
Domestically, market players are awaiting Indonesia’s inflation data, which is expected to rise to 0.2 per cent month-on-month (m-o-m) in August 2026, following a deflation of 0.14 per cent (m-o-m) in July 2026. On an annual basis, inflation is projected to reach 3.13 per cent year-on-year (y-o-y) in August 2026, up from 2.88 per cent (y-o-y) in July 2026. Core inflation is also expected to rise to 2.8 per cent (y-o-y) in August 2026, from 2.76 per cent (y-o-y) previously.
Furthermore, investors are anticipating trade balance data, which is expected to record a deficit of US$0.3 billion in July 202_6, an improvement from the US$0.45 billion deficit recorded in June 2026. Import growth is expected to remain higher than export growth, while the Manufacturing PMI index is estimated to rise slightly to 50.5 in August 2026 from 50.2 in July 2026.
Across Asia, market participants are awaiting China’s Caixin Manufacturing PMI data, which is expected to rise to 51 in August 2026 from 50.9 in July 20_. Meanwhile, Japan’s Consumer Confidence index is estimated to rise slightly to 35 in August 2026.
In Europe, investors are watching Eurozone inflation data, which is expected to rise to 3.3 per cent (y-o-y) in August 2026, up from 2.9 per cent (y-o-y) previously. In the United States, the ISM Manufacturing PMI is expected to decline slightly to 55.2 in August 2026 from 55.6 in July 2026, while US job openings are projected to be at 7.3 million in July 2026, down from 7.36 million in June 2026.
Regarding geopolitical sentiment, US attacks on Iran have triggered a rebound in oil prices. If oil prices remain high for an extended period, it could potentially drive up inflation rates once again. Meanwhile, the US Federal Reserve has signalled a focus on bringing inflation down to its target, increasing expectations that the Fed may raise interest rates in September 2026.
Additionally, market participants are closely observing the meeting of finance ministers, central bank governors, and other officials from G20 nations in Asheville, North Carolina, USA. Investors will also monitor a series of economic data releases for clues regarding US monetary policy direction, including the US non-farm payrolls (NFP) data to be announced on Friday (4/9/2026).
Crude oil prices closed up more than 2 per cent on Monday (31/8/2026) after US forces attacked two Iranian rocket launchers on Larak Island, marking a return of hostilities between the US and Iran. Meanwhile, the US 10-year Bond Yield rose by 2 bps to 4.75 per cent as investors monitored Middle East developments and the G20 financial leaders’ meeting.
European markets moved variably on Monday (31/8/2026); the Euro Stoxx 50 rose 1.07 per cent, the UK FTSE 100 rose 0.29 per cent, the German DAX fell 1.17 per cent, and the French CAC 40 fell 0.79 per cent. Wall Street indices all declined on Monday (31/8/2026), with the S&P 500 falling 0.33 per cent to 7,686.14, the Nasdaq Composite dropping 0.12 per cent to 26,370.89, and the Dow Jones Industrial Average losing 0.70 per cent to 53,185.90.
Regional Asian markets this morning showed weakness, with the Nikkei falling 0.33 per cent to 65,093.00, the Shanghai Composite down 0.17 per cent to 3,979.4, the Kospi down 0.52 per cent to 6,784.28, the Hang Seng down 1.22 per cent to 25,255.00, and the Straits Times index down 0.48 per cent to 5,727.47.