
IDX Composite Slightly Corrects 0.11% to Level 6,660 in Morning Session
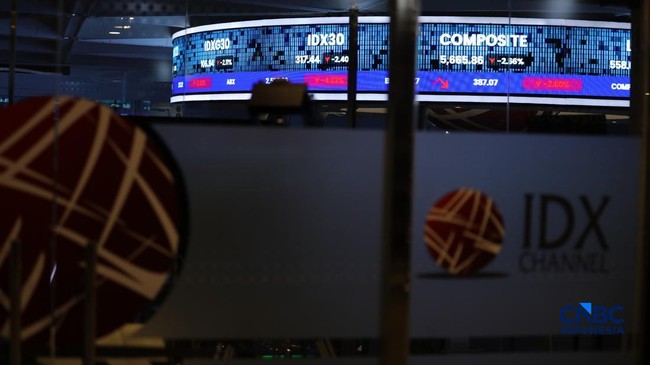
The Indonesia Composite Index (IHSG) underwent a slight correction and failed to continue its recent gains during trading on Friday (4/9/2026). The IHSG fell by 7.10 points, or 0.11%, to the level of 6,660.79.
According to data from the Indonesia Stock Exchange, the IHSG opened at 6,695.69, reaching an intraday high of 6,704.13 and a low of 6,637.48. During the session, 266 stocks strengthened, 325 stocks weakened, and 196 stocks remained stagnant. Trading volume in the early session reached 1.02 billion shares, with a transaction value of approximately Rp529 billion.
Following the gains on Thursday (3/9/2026), where the IHSG closed up 1.09% to 6,667.89 supported by heavy net foreign buying of around Rp1.07 trillion and the strength of several large-cap stocks, the index faced pressure today. Most trading sectors weakened, with the deepest corrections recorded in the consumer, healthcare, industrial, and technology sectors, while the energy sector recorded the highest increase.
Specifically, the issuers that acted as the main drags on the IHSG’s movement today included ASII, SRAJ, VKTR, BRMS, and INDF.
The IHSG has the potential to continue its upward trend in Friday’s trading, supported by several positive domestic sentiments and developments in United States monetary policy. Domestically, the liquidity relaxation from Bank Indonesia (BI) serves as a primary catalyst. BI has increased the Macroprudential Liquidity Incentive (KLM) policy to 6% starting in September, with total incentives received by the banking sector reaching Rp446.5 trillion. This policy is expected to encourage credit distribution, particularly to the real sector and MSMEs.
Other positive sentiments include tax incentives on foreign currency SBN (Government Securities) interest, while the government has ensured that the financing for the ‘Koperasi Desa Merah Putih’ programme will not become non-performing loans for the banking sector.
Externally, market attention is focused on US labour market data tonight, particularly non-farm payrolls (NFP), the unemployment rate, and wage growth. This data will be a key determinant for the direction of the Federal Reserve’s policy. Positive sentiment also stems from statements by Fed Governor Christopher Waller, who tends to support maintaining interest rates at current levels in September if subsequent inflation data does not provide surprises. However, the market remains cautious regarding labour data, as excessively strong results could potentially maintain inflationary pressure and expectations for higher interest rates for longer.
Meanwhile, US economic data shows that jobless claims remain low, but the services sector is strengthening, with the ISM Services PMI reaching 55.4 in August. On the other hand, rising price pressures are providing mixed signals for the Fed.