
How to Clear Your Name from OJK's SLIK (Formerly BI Checking)
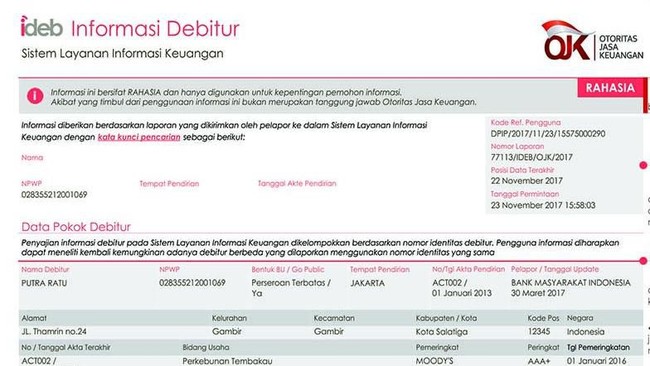
Jakarta, CNBC Indonesia – A credit history in the Financial Services Authority’s (OJK) Financial Information Service System (SLIK), previously known as BI Checking, is one of the main factors determining whether a person can obtain financing from banks or other financial institutions.
The worse a person’s credit score, the smaller their chances of securing a loan. In fact, loan data from online lending services (P2P lending) is now also recorded in SLIK OJK, so payment histories on these platforms affect credit assessments.
Before this rule was implemented, the Indonesian Real Estate Association (REI) revealed that around 40% of mortgage (KPR) applications were rejected because applicants had poor credit scores. One of the causes was arrears on online lending platforms.
Beyond affecting access to financing, OJK has also highlighted cases of job seekers who failed to secure employment due to problematic credit records in SLIK.
Agusman, Executive Head of Supervision for Financing Institutions, Venture Capital Companies, Microfinance Institutions and Other Financial Services Institutions at OJK, said that SLIK data can be updated once a borrower has made payments or taken steps in accordance with applicable regulations.
Members of the public can now also check their SLIK status independently. Prospective borrowers should therefore find out the state of their credit history before applying for a new loan.
According to the Pegadaian website, SLIK OJK scores are divided into five categories. A score of 1 indicates the best credit history, while a score of 5 denotes non-performing credit.
It should be noted that only borrowers with scores of 1 and 2 can generally apply for bank credit without difficulty. Meanwhile, customers with scores of 3, 4 and 5 need to repair their credit records first.
To find out their credit score, the public can access the official iDebKu service at idebku.ojk.go.id.
So, what if you already have a poor credit record?
If you still have outstanding loan arrears, the only way to clean up your credit record is to settle all outstanding obligations in full.
However, if the arrears record arose due to a data error, the borrower can contact or report the problem to the relevant party so that a correction can be made.
Generally, SLIK OJK data is updated within a maximum of 30 days after an obligation is settled. Borrowers are also advised to request a letter of settlement (SKL) as proof when applying for a new loan or credit.