
Get Ready: Global Central Banks Set to Influence Markets Next Week
Trading from 26 to 30 October 2026 will be shaped by a series of central-bank decisions and major economic releases.
The main focus will be on the Federal Reserve, the European Central Bank (ECB) and the Bank of Japan (BOJ), all facing the challenge of balancing economic growth with inflation control.
Meanwhile, economic growth data from the United States and the eurozone will test the resilience of business activity amid global uncertainty.
These developments could affect the rupiah, bond yields and foreign capital flows. The busiest part of the calendar falls on Thursday and Friday, when changing expectations for monetary policy could trigger sharper market moves towards the end of the week.
China’s industrial profits, September 2026
China is scheduled to release industrial profits for January to September on Tuesday at 8.30 am WIB. The benchmark is year-on-year growth of 15.7% in January to August, slowing from 17.6% in January to July. No market consensus for the latest release has been published.
The data will show whether industrial companies can maintain profitability while the recovery in demand remains uneven.
Markets will also need to distinguish cumulative profit growth since the start of the year from performance in September alone. Improving profitability could support investment expectations and demand for raw materials, while a further slowdown could raise concerns about the outlook for Chinese commodity demand.
Federal Reserve interest-rate decision, October 2026
The Fed’s decision is scheduled for 1.00 am WIB on Thursday, followed by a press conference at 1.30 am. The consensus forecast is for rates to remain in the 3.75%–4.00% range, following a 25-basis-point increase in September.
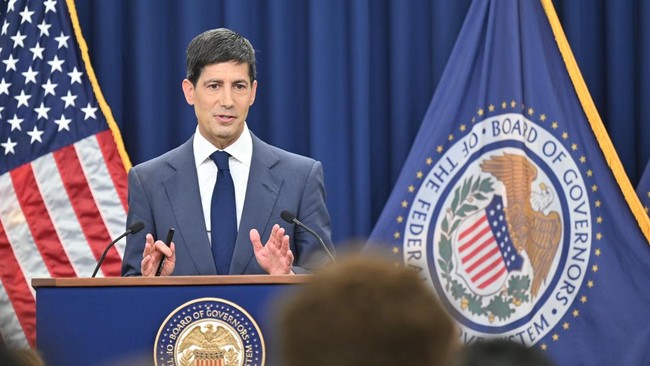
Alongside the decision, markets will scrutinise Fed Chair Kevin Warsh’s assessment of inflation and employment, and the possibility of further tightening.
Warsh has not previously given a clear indication of the outcome of the October meeting and has stressed that price pressures remain high. As a result, holding rates steady would not automatically signal that the rate-hiking cycle is over.
Markets will also watch for changes in the wording of the policy statement. Language that leaves the door open to further tightening could support the dollar and weigh on risk assets.
Conversely, greater emphasis on the risk of an economic slowdown could reduce expectations of another increase. For Indonesia, these shifts matter for the rupiah and the appeal of domestic bonds.
US economic growth, third quarter 2026
The preliminary estimate of US economic growth is due at 7.30 pm WIB on Thursday. The consensus forecast is for growth of 3.2% at an annualised quarterly rate, up from 2.2% in the previous quarter. This is not growth compared with the same period a year earlier.
Beyond the headline figure, markets will examine the breakdown of consumption, investment, trade and inventories to assess the quality of growth. An expansion driven by sustained domestic demand presents a different picture from one boosted by temporary factors.
A result above expectations could reinforce the view that the economy remains resilient despite high interest rates, although the market response will still depend on inflation developments.
US PCE inflation, September 2026
Alongside GDP, core PCE inflation is forecast to rise to 0.3% month on month from 0.2%, and to 3.1% year on year from 3.0%. The core measure excludes food and energy to help gauge underlying price pressures.
The release comes after the Fed’s decision, so it will be more relevant to expectations for the next meeting than to the decision already announced. A reading above consensus could sustain concerns about persistent inflation and constrain hopes for monetary easing.
A lower figure, by contrast, could give markets room to judge that price pressures are beginning to ease, although consistency over several months would still be needed.
ECB interest-rate decision, October 2026
Also on Thursday, the ECB will announce its decision at 8.15 pm WIB, followed by a press conference at 8.45 pm. The consensus forecast is for the main refinancing rate to remain at 2.65% and the deposit facility rate at 2.50%.
The focus will be on how the ECB responds to inflation risks while growth slows. A decision to hold rates needs to be considered alongside the bank’s guidance, particularly on the prospect of further tightening and its assessment of energy-cost pressures.
For global markets, a change in the ECB’s tone could affect the euro, European bonds and the dollar’s relative performance. As the announcement comes close to major US releases, investors will need to consider the combined impact rather than assess either development in isolation.
Japan’s unemployment rate, September 2026
Japan’s unemployment rate is forecast to remain at 2.5% on Friday at 6.30 am WIB, unchanged from August. The jobs-to-applicants ratio is also expected to hold at 1.18, equivalent to about 118 vacancies for every 100 applicants.
The employment data will provide important context ahead of the BOJ’s decision, particularly in assessing labour demand and its contribution to wage growth.
A tight labour market could support consumption, but may also keep pressure on companies’ costs. The unemployment rate should therefore be considered alongside changes in the number of workers and labour-force participation.
Japan’s retail sales, September 2026
Retail sales, released alongside industrial production, are forecast to grow 3.3% year on year, up from 2.7% in August. The release will offer a picture of consumers’ ability to keep spending amid price pressures.
However, an increase in the value of sales does not necessarily indicate an equivalent rise in consumption volumes, as inflation can also affect the figure. The sales breakdown and monthly trend will help clarify the underlying picture.
For markets, broader consumer strength could support an assessment of the domestic economy’s resilience, while a weak result could give the BOJ further reason to proceed cautiously.
BOJ interest-rate decision, October 2026
After the morning’s data releases, the BOJ is expected to announce its decision at around 10.00 am WIB on Friday, although the timing may change. The consensus forecast is for rates to remain at 1.25%, following an increase from 1.00% in September.
The BOJ is also due to publish its economic and price outlook. Markets will watch for changes to its projections and indications of the pace of future policy normalisation, including its assessment of wages, consumption and price pressures.
The combination of the decision and the BOJ’s communication could affect the yen and investment strategies that exploit interest-rate differentials between countries.
A more hawkish policy stance could draw greater attention to the narrowing gap between Japanese rates and those elsewhere.
However, a decision to hold rates should not be confused with a commitment not to raise them at the next meeting.
Eurozone economic growth, third quarter 2026
The preliminary eurozone GDP estimate is due at 5.00 pm WIB on Friday and is forecast to show quarterly growth of 0.2%, down from 0.6%. The consensus forecast for annual growth is 1.1%, compared with 1.2% previously.
A slowdown in line with expectations would highlight the ECB’s challenge in controlling inflation without further burdening economic activity. Markets will also use the latest figures to assess the central bank’s communication from the previous day.
Growth below consensus could intensify concerns about the resilience of the region, while a stronger result could ease worries about a slowdown, though it would not automatically change the policy direction.
Eurozone unemployment rate, September 2026
At the same time, the eurozone unemployment rate is expected to remain at 6.4%, unchanged from August. A stable labour market could help support incomes and consumption as economic growth slows.
By contrast, an increase above consensus could fuel concerns that cost pressures and interest rates are having a greater effect on hiring. Markets should read this data alongside GDP, as the two measures capture different aspects of economic resilience.
Slowing growth accompanied by stable unemployment sends a different signal from a slowdown that also comes with declining labour absorption.