
Expansion Imminent Under New Controller: A Profile of DPUM and Its Latest Performance
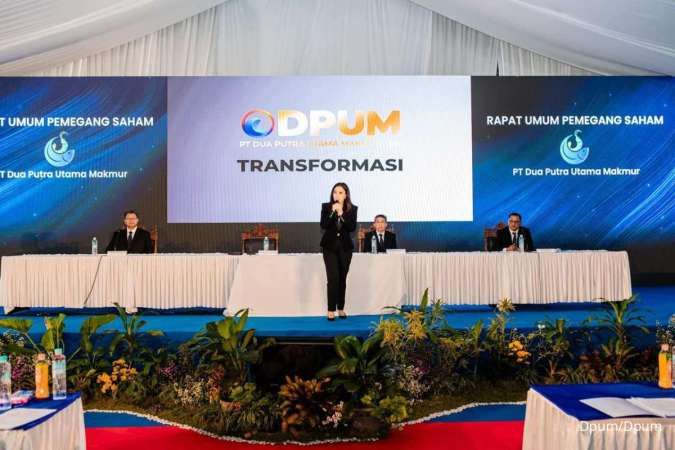
PT Dua Putra Utama Makmur Tbk (DPUM) has become a focal point for investors following a change in control scheduled for 2026. According to announcements from the Indonesia Stock Exchange (BEI), this transition occurs after PT Rama Indonesia acquired a 59.24% stake in DPUM from PT Pandawa Putra Investama in May 2026.
The entry of Rama Indonesia, part of the Unirama Group, brings a new strategic direction for DPUM. In addition to maintaining its core business in the fisheries and seafood processing sector, the new controller is preparing investments and operational reinforcements to drive business recovery and expansion.
Recently, DPUM has prepared a capital expenditure (capex) of approximately Rp100 billion for 2026. The company also targets an average EBITDA growth of 7.75% per annum during the 2027-2030 period.
The change in control was finalised after PT Rama Indonesia completed the purchase of 2.473 billion shares, equivalent to 59.24% of DPUM’s fully paid-up capital. The transaction was executed on 8 May 2026 at a price of Rp88 per share, bringing the total transaction value to approximately Rp217.65 billion, establishing Rama Indonesia as the new controlling shareholder.
Rama Indonesia is part of the Unirama Group, a business group involved in providing supply chain solutions and the distribution of fast-moving consumer goods (FMCG). This change in control is also accompanied by a plan for a Mandatory Tender Offer (MTO) for DPUM shares held by public shareholders. The tender period is scheduled to run from 24 September 2026 to 23 October 2026, with transaction settlement and payment slated for 9 November 2026, subject to OJK regulations.
The arrival of the new controller brings several development plans for DPUM’s business. One of the most significant is the allocation of Rp100 billion in capex for 2026. These funds are directed towards business development, facility optimisation, increasing operational capacity utilisation, and the restoration of facilities affected by fire.
Furthermore, Unirama Group identifies synergy opportunities through its supply chain and distribution networks. Such synergies are expected to assist DPUM in strengthening its supply chain, expanding distribution networks, increasing operational efficiency, improving production facility utilisation, restoring fire-damaged facilities, and expanding the market for fishery products.
DPUM also targets an average EBITDA growth of 7.75% per annum for 2027-2030 as part of its post-control change development strategy. According to IPOT data, DPUM’s share price experienced a decline during the first session on Thursday (17/9), dropping by Rp150 per share or 5.66%.
DPUM operates in the fisheries and seafood processing sector. Its business model includes processing fishery products to meet both domestic and export market demands. Its product lines include fish, tuna, squid, octopus, frozen fish, and other processed seafood products.
With the entry of Unirlam Group, distribution networks and supply chains are key areas for potential development, though the realisation of these synergies depends on the execution of the company’s strategies and operational progress.
Regarding recent financial performance, DPUM faced pressure in the first half of 2026. Based on the Q2 2026 financial reports, the company’s revenue was recorded at Rp407.5 billion, a 29.5% decrease compared to Rp577.8 billion during the same period the previous year. Despite the drop in revenue, gross profit increased to Rp23.3 billion, compared to Rp11.9 billion in the first half of 2025. However, DPUM recorded a net loss of Rp31 billion, reversing from a net profit of approximately Rp82.4 million in the first half of 2025. EBITDA also turned negative at Rp1 billion, down from a positive Rp22.3 billion in the previous period.