
DPR Commission XI Chief Confirms PFII Will Continue to Refer to GMT Agreement
The government has confirmed that various tax incentives prepared for investors in the Indonesian International Financial Centre (PFII) will remain in line with the Global Minimum Tax (GMT) provisions that Indonesia has adopted. The policy is designed to maintain investment appeal while fulfilling international tax commitments.
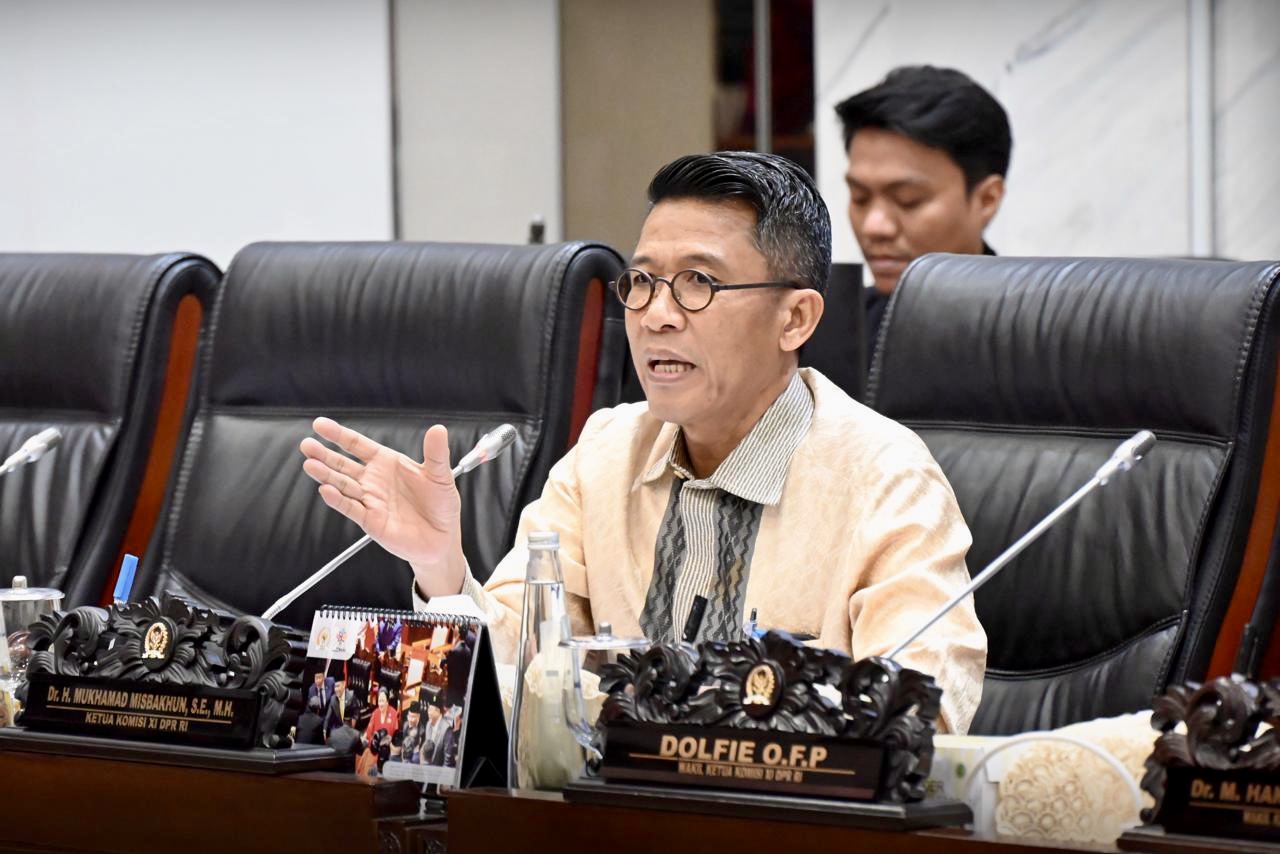
Chairman of House Commission XI, Mukhamad Misbakhun, stated that the provisions regarding tax incentives for investors are already regulated by law. However, their implementation will continue to consider the evolving global tax regime now applied in many countries.
“The law stipulates that investors are granted a 50-year tax holiday. But we certainly know there have been changes in the international tax landscape, and we are following all of that,” Misbakhun told CNBC Indonesia on Thursday.
He explained that the application of tax facilities will be adjusted based on the status of companies investing in the PFII, particularly whether they fall under the scope of the Global Minimum Tax or not.
“The mechanism is already in place. We just need to see whether the companies that will invest in the PFII fall within the scope of the global minimum tax. If not, they can still enjoy the 50-year tax holiday,” Misbakhun asserted.
The Global Minimum Tax is an international agreement that has been implemented in more than 60 countries. Indonesia began enforcing the policy on 1 January 2025, in line with several other nations such as Singapore, Malaysia, Hong Kong, and the United Arab Emirates.
In its implementation at the PFII, the GMT applies to Multinational Enterprises (MNEs) with a global turnover of at least 750 million euros. The global minimum tax is applied through three mechanisms: the Qualified Domestic Minimum Top-up Tax (QDMTT) collected by the country where the subsidiary operates, the Income Inclusion Rule (IIR) imposed by the parent company’s country of domicile, and the Undertaxed Payment Rule (UTPR) applied by other group member countries.
These provisions do not create an additional tax burden for individual business actors or companies that are not part of MNE groups with a global turnover below 750 million euros. Furthermore, companies in the PFII with an effective tax rate above 15 percent after consolidation with their business entities in Indonesia will also not be subject to additional tax.
In addition to the tax holiday incentive, the government has also prepared various other fiscal facilities for investors, business actors, and professionals operating in the PFII area.
“Besides the tax holiday, investors, business actors, and professionals there are also provided with other facilities such as income tax exemptions for foreign taxpayers, as well as various VAT and luxury goods sales tax facilities,” he explained.
The PFII is the implementation of Article 248A of Law Number 4 of 2026 concerning Amendments to Law Number 4 of 2023 on Financial Sector Development and Strengthening (P2SK). This regulation mandates the establishment of a separate legal framework for the operation of the Indonesian International Financial Centre.
The existence of the PFII is expected to become a driving force for strengthening the national financial sector through financial market deepening, expansion of instruments and financing sources, increased investment flows, and strengthening Indonesia’s position in the global financial ecosystem.
Source: jawawa.id (https://jawawa.id/newsitem/dpr-commission-xi-chief-confirms-pfii-will-continue-to-refer-to-gmt-agreement-1784911839)
Originally published by fraksigolkar.com (https://fraksigolkar.com/read/2360/ketua-komisi-xi-dpr-ri-pastikan-pfii-tetap-mengacu-pada-kesepakatan-gmt), translated from Indonesian