
CORE: Alternative Credit Scoring Can Expand MSME Financing
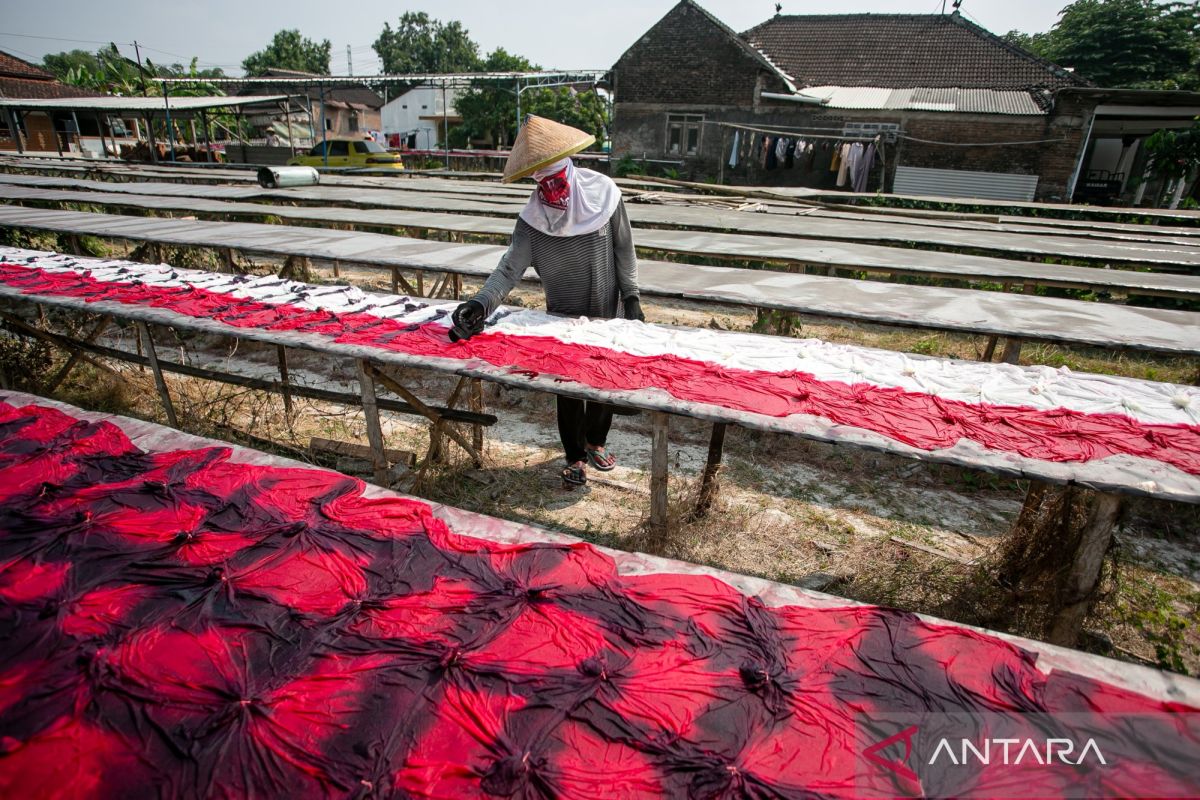
Jakarta (ANTARA) - Mohammad Faisal, Executive Director of the Center of Reform on Economics (CORE) Indonesia, believes that the use of alternative credit scoring can help expand financing access for micro, small and medium enterprises (MSMEs).
According to Faisal, this credit assessment system is one of the innovations that can match micro business owners with financing schemes suited to the characteristics and needs of their businesses.
“I see it as one form of innovation to break through access to financing for businesses, especially micro enterprises — not just MSMEs in general, but more specifically micro businesses, which currently still face relatively limited financing,” Faisal told ANTARA in Jakarta on Tuesday.
He said alternative credit scoring can serve as an option for micro business owners who do not yet have a credit track record or collateral, making it easier for them to obtain financing.
“I think it is one of the innovations to match micro business owners with financing that suits them — financing that is suitable, workable, and doable,” he said.
Nevertheless, Faisal believes the expansion of financing access must be accompanied by stronger market access so that micro businesses can grow sustainably.
He noted that market access remains the main challenge faced by micro enterprises, while financing is the next challenge.
“If asked what the biggest obstacle is, in my view it is the market. So market access is what first needs to be boosted and expanded, and then financing comes second,” he said.
He added that the success of micro businesses is largely determined by their ability to expand their markets, as demand for products is a key factor in sustaining a business.
The Financial Services Authority (OJK) previously strengthened its strategy to expand MSME financing access through the use of alternative credit scoring.
As of July 2026, eight Alternative Credit Rating Providers (PKA) have been registered with the OJK, supported by 17 data aggregators that assist in the creditworthiness assessment process.
According to the OJK, the scheme is expected to open up financing access for business owners who have neither a credit history nor collateral.
Credit assessments are carried out using alternative data outside of banking credit information, giving financial institutions an additional basis for evaluating the creditworthiness of prospective borrowers.
The scheme has also been piloted among dairy cattle farmers in Malang, using an Enterprise Resource Planning (ERP) system that connects business data with financing institutions.
The OJK projects MSME lending to grow by 7-9 per cent in 2026. To support this target, the regulator is encouraging the development of financing business models, optimisation of credit scoring, as well as MSME segmentation and profiling to expand inclusive financing access.
Source: jawawa.id (https://jawawa.id/newsitem/core-alternative-credit-scoring-can-expand-msme-financing-1785808354)
Originally published by Antara (Indonesian) (https://www.antaranews.com/berita/5678651/core-penilaian-kredit-alternatif-dapat-perluas-pembiayaan-umkm), translated from Indonesian