
Coal Prices Surge for 7 Consecutive Days, Approaching US$ 150, Driven by Indonesian Supply Constraints
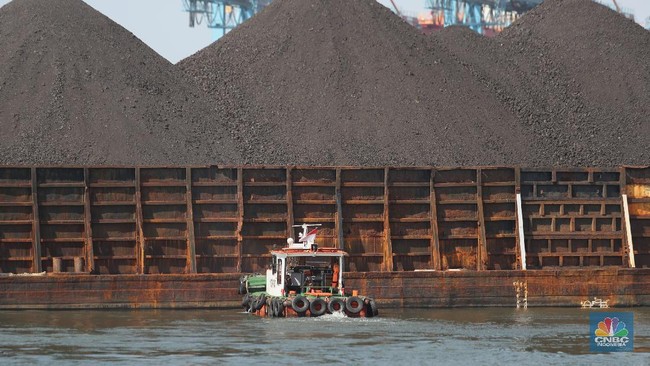
Coal prices continue to soar amidst rising oil prices and supply concerns. On Wednesday (2/9/2026), coal prices closed at US$ 148.9 per troy ounce, marking a 0.78% increase. This rise extends a positive trend, with prices strengthening by 7.6% over six consecutive days. The closing price yesterday was the highest since 11 June 2026.
The increase in coal prices is partly supported by oil prices. West Texas Intermediate (WTI) closed up nearly 1% to US$ 91.01 per barrel, while Brent strengthened by approximately 1% to US$ 95.63 per barrel. As coal and oil are substitute commodities, their prices influence one another.
Thermal coal markets at Chinese ports have strengthened due to tightening supplies. Inflow of coal via rail to northern Chinese ports remains low, limiting supplies at major ports. However, the price increase faces buyer resistance, as consumers tend to hold back purchases because prices have risen quite rapidly. This situation leaves the market in a state of tight supply, but with demand not yet strong enough to support a further rally.
Previously, at the end of August, thermal coal prices at northern Chinese ports were reported to have hit a two-year high, with the increase spreading to the imported coal market. The price hike in China was primarily triggered by supply tightness at the mine level. Several mines are still facing production restrictions and safety inspections, while others have already met their August production targets. Weather disruptions have also limited mining and distribution activities. Simultaneously, imported coal supplies from Indonesia are also constrained by delays in the approval of Work Plans and Budget Plans (RKAB) and transport disruptions caused by drought.
While demand from the electricity sector has begun to decline from its summer peak, it remains sufficiently strong. Daily coal consumption by power plants across six major coastal plant groups in China remains above 940,000 tonnes. In addition to power plants, demand from the chemical, construction materials, and industrial sectors is also supporting the market, with some companies even beginning restocking for winter needs.
However, the price increase is considered not to fully reflect a surge in demand. Bullish sentiment and supply limitations are the more dominant factors. Supplies are expected to begin improving entering September as several mines resume operations and weather disruptions subside. Therefore, the sustainability of the price rally will depend heavily on how strongly consumer demand can absorb the price increases.
The European thermal coal market is also strengthening entering September 2026. Geopolitical tensions in the Middle East, depleting gas reserves, weather disruptions, and the tightening of global coal supplies have once again increased the value of coal as an energy source for the 2026-2027 winter season. The strengthening of European coal is primarily driven by the gas market. Middle East conflicts and uncertainty in the Strait of Hormuz increase the risk to LNG supplies, while European gas reserves are relatively low.
European gas storage was only about 62% full at the end of August, making the region vulnerable if winter arrives early or if LNG supply disruptions continue. This condition is driving winter gas prices up and making coal-fired power plants more economical compared to gas.
Global supplies are becoming increasingly tight, including from Indonesia. Supply disruptions in South Africa and Indonesia, combined with rising demand from China, are intensifying competition in the seaborne coal market. In South Africa, disruptions to the rail line to Richards Bay are weighing on supply. Meanwhile, Pakistan became the largest buyer of South African coal in the final week, intensifying competition with European buyers.
In Indonesia, delays in the approval of the Work Plan and Budget Plan (RKAB) and transport disruptions due to low water levels in the Barito River are also limiting supplies. China is also experiencing an increase in domestic coal prices due to reduced availability at northern ports. The price increase in Europe has made coal from Colombia and the United States competitive once again. US coal exports rose 19.1% year-on-year to 24.4 million tonnes in Q2-2026. The price of New Orleans 6,000 NAR coal also surged from US$ 85.5 to US$ 92.9/tonne between 26 August and 1 September.
Consequently, European coal prices have the potential to compete with the Asian market for additional supplies. The outlook for European coal now depends heavily on gas reserves, Middle East LNG supplies, winter temperatures, renewable energy generation, and global coal availability. If the winter is mild and LNG supplies improve, the coal price increase could subside. However, a cold winter with low wind, combined with prolonged LNG disruptions, could once again drive coal demand.