
Coal Holds Near Highest Level, Gold Price Under Pressure
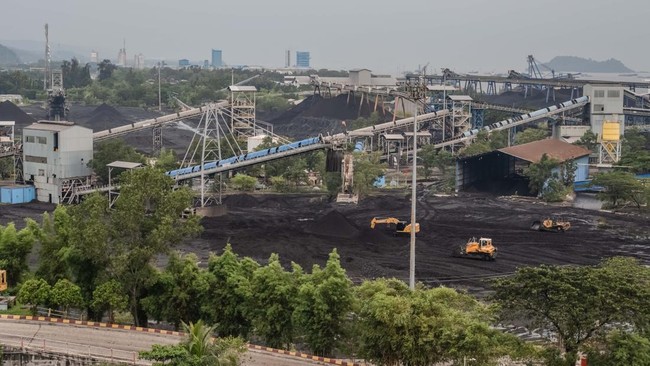
Jakarta, CNBC Indonesia - Global coal prices closed the week with a slight correction but remained at their highest level in nearly two years. Based on Refinitiv data, the Newcastle futures contract closed at US$145 per tonne on Thursday (12/6/2026), down 2.39% compared to the previous day. Despite weakening at the end of the week, coal still posted a weekly gain of 1.7% compared to the position of US$142.5 per tonne the previous week. Throughout this week’s trading, the price touched US$150.35 per tonne, the highest level since September 2023.
The price increase in recent weeks stemmed from market concerns over global supply. Indonesia, the world’s largest exporter of thermal coal, has tightened export supervision of the commodity. This policy raises the risk of delays in coal shipments to the international market at a time when seasonal demand is starting to increase. The northern hemisphere is now entering summer. Electricity consumption for air conditioning is rising in several Asian countries. The need for power generation has also increased, so coal demand is supported by energy consumption.
The global energy market is also still adapting to the impact of the Middle East conflict. The months-long closure of the Strait of Hormuz has disrupted energy flows from the Persian Gulf region. This condition has prompted several importing countries to seek alternative energy sources to maintain supply security. Japan and South Korea are among the countries that have increased coal use since the conflict broke out. This choice emerged after supplies of liquefied natural gas (LNG) from the Gulf region faced obstacles. Qatar’s Ras Laffan facility even declared force majeure, reducing LNG supply to Asia by approximately 10.2 million tonnes per year. This disruption is expected to last until the end of summer.
This change in energy consumption patterns provides room for coal to maintain prices at high levels. Amid tighter gas supply conditions, a number of power plants are returning to rely on coal to maintain electricity availability and reduce energy costs. Although prices corrected in the last two sessions, coal’s current position is still about 41% higher compared to the same period last year. The market’s near-term focus remains on supply developments from Indonesia and the energy situation in the Middle East. As long as these two factors have not subsided, coal prices have the potential to remain at high levels.
Gold Pressured by Interest Rates, Price Plunges Nearly 6%
Global gold prices again closed the week in the red. Based on Refinitiv data, spot gold was at US$4,218.77 per troy ounce on Thursday (12/6/2026), up slightly by 0.12% compared to the previous day. This daily increase was not enough to change the weekly direction. Over the week, gold slumped 5.6% from the position of US$4,473.89 per troy ounce on 4 June.
The weakening of gold occurred amid a major shift in market expectations regarding the direction of United States (US) monetary policy. Since the beginning of the year, investors had expected the Federal Reserve to cut interest rates several times. Now the scenario has reversed. Reheating inflation and a persistently strong labour market have brought the possibility of interest rate hikes back into market calculations. Recent economic data triggered this. US consumer inflation in May recorded the fastest pace in three years. Producer prices also rose 6.5% year-on-year. The Iran conflict, ongoing since February, has also pushed up energy costs and reinforced price pressures across various economic sectors. These conditions have led the market to begin doubting the room for the Fed to loosen its monetary policy this year.
This shift in expectations is reflected in the CME FedWatch. The probability of an interest rate hike in December is now above 50%. Higher interest rates increase the attractiveness of US government bonds and dollar-based instruments. As a result, funds are flowing out of non-yielding assets like gold. The pressure intensified after gold broke through the 200-day moving average for the first time since 2023. This technical level, which had been a market defence area for nearly two and a half years, has now turned into a barrier to gains. Reuters reported that the gold price touched US$4,022 per troy ounce on Thursday, the lowest level since November last year.
Investor fund flows have also begun to change direction. Standard Chartered estimates that hundreds of tonnes of gold in ETFs are now in a loss position after the price fell below US$4,250 per troy ounce. Market data shows gold-backed ETFs experienced outflows of 16 tonnes during May and an additional 7 tonnes in the first week of June. JPMorgan even recorded outflows from gold ETFs reaching approximately US$20 billion up to early June. Despite this, the long-term outlook for gold has not changed drastically. Citi assesses that central bank purchases, high government debt, foreign exchange reserve diversification, and global geopolitical uncertainty remain the main pillars of demand for the precious metal. These factors drove gold to set records throughout 2025, briefly touching a historic peak of US$5,608 per troy ounce in January this year.
The market’s focus is now on the Federal Reserve meeting on 16-17 June, the first meeting under the leadership of Kevin Warsh. The market expects interest rates to be held in the 3.50%-3.75% range. However, what is more important is the indication of the next policy direction. As long as inflation remains high and the US dollar stays strong, the room for gold’s recovery is expected to remain limited.