
Citi Indonesia Reveals Global and Domestic Factors That Could Ease Pressure on the Rupiah
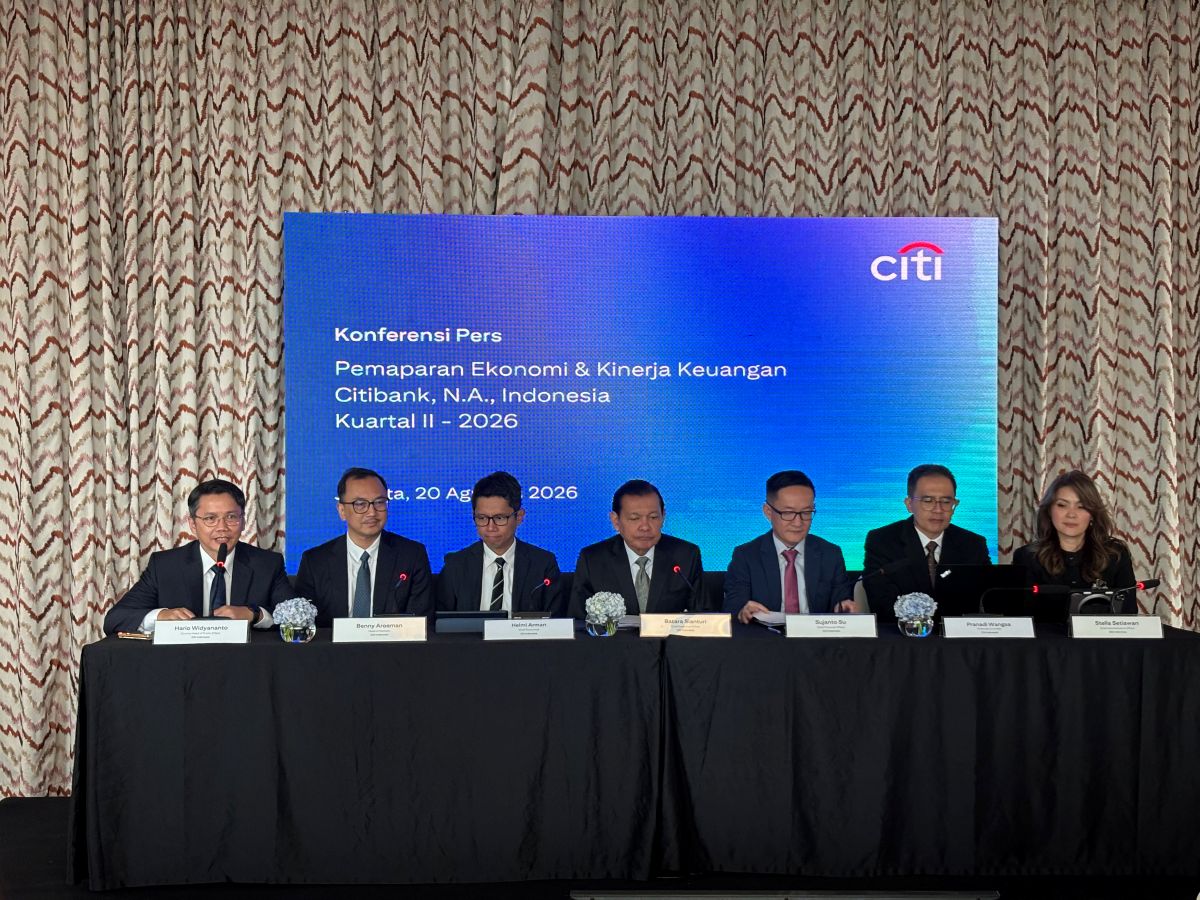
Chief Economist of Citi Indonesia, Helmi Arman, has stated that various global and domestic factors could support a reduction in pressure on the rupiah exchange rate. On the global side, Helmi noted that the trend in world oil prices is expected to be relatively lower compared to the previous quarter, although it will not return to pre-conflict levels in the near term. Citi’s commodities team estimates that if oil trade flows through the Strait of Hormuz fully return to normal, the global oil market will be in surplus, with supply exceeding demand. The surplus is expected to be larger than before the conflict, reaching around 4 million barrels per day by 2027, assuming the strait returns to normal. This is the first global factor: a declining trend in world oil prices.
A second global factor is Citi’s expectation that US Treasury yields, particularly for shorter tenors, will decline towards the end of the year. Citi’s view is that the Federal Reserve will not raise interest rates and may even cut them before year-end, as core inflation in the United States is on a downward trend, expected to fall from around 2.5% to 2.2% or 2.3%. Helmi explained that the decline in US core inflation is partly due to relatively weak consumer demand, even though overall US economic growth remains relatively strong, supported mostly by AI investment.
Another global factor supporting reduced pressure on the rupiah towards the end of the year is Citi’s forecast that the dollar will weaken against the euro. The dollar index, known as DXY, is expected to decline due to differing interest rate expectations between the US and Europe, with the ECB expected to raise rates in September while the US does not. Citi also predicts the dollar will weaken against the Chinese yuan, as China’s current account surplus remains relatively strong, exceeding 3% of its GDP.
On the domestic side, Helmi said the decline in world oil prices will reduce Indonesia’s current account deficit in the third quarter compared to the second quarter. Although second-quarter current account data is not yet available, Citi estimates the deficit was quite large, above 2% of GDP. In the second half of the year, the current account deficit is expected to narrow to around 1.5% of GDP, in line with lower oil prices. This narrowing is already visible in June trade data, where the deficit was smaller than in May. Helmi stressed that the rupiah’s depreciation since the end of last year means foreign investment dividends repatriated abroad in dollar terms become smaller, which will also help reduce the current account deficit in the third quarter.
Furthermore, Helmi observed that foreign investor appetite for government bonds (SBN) has increased in the third quarter compared to the second quarter. Domestic factors supporting this trend include the 2026 state budget deficit not being as large as previously expected, as the government has released its 2026 outlook showing the deficit remains below 3% of GDP. This is due to reductions and delays in certain spending, including MBG spending, as well as accelerated tax revenue collection. The planned 2027 state budget deficit is also expected to remain below 3% of GDP. Bond investors consider this as reducing the risk of oversupply of government bonds in the market, whereas previously they were concerned about oversupply if the deficit exceeded 3% of GDP.