
Bank Indonesia notes positive foreign investor interest in hedging cost incentives
Bank Indonesia (BI) assesses that non-resident investor interest in the policy to increase hedging cost incentives through swap instruments and Domestic Non-Deliverable Forward (DNDF) has been quite positive so far. BI noted that this policy has also supported foreign capital inflows into the Indonesian financial market.
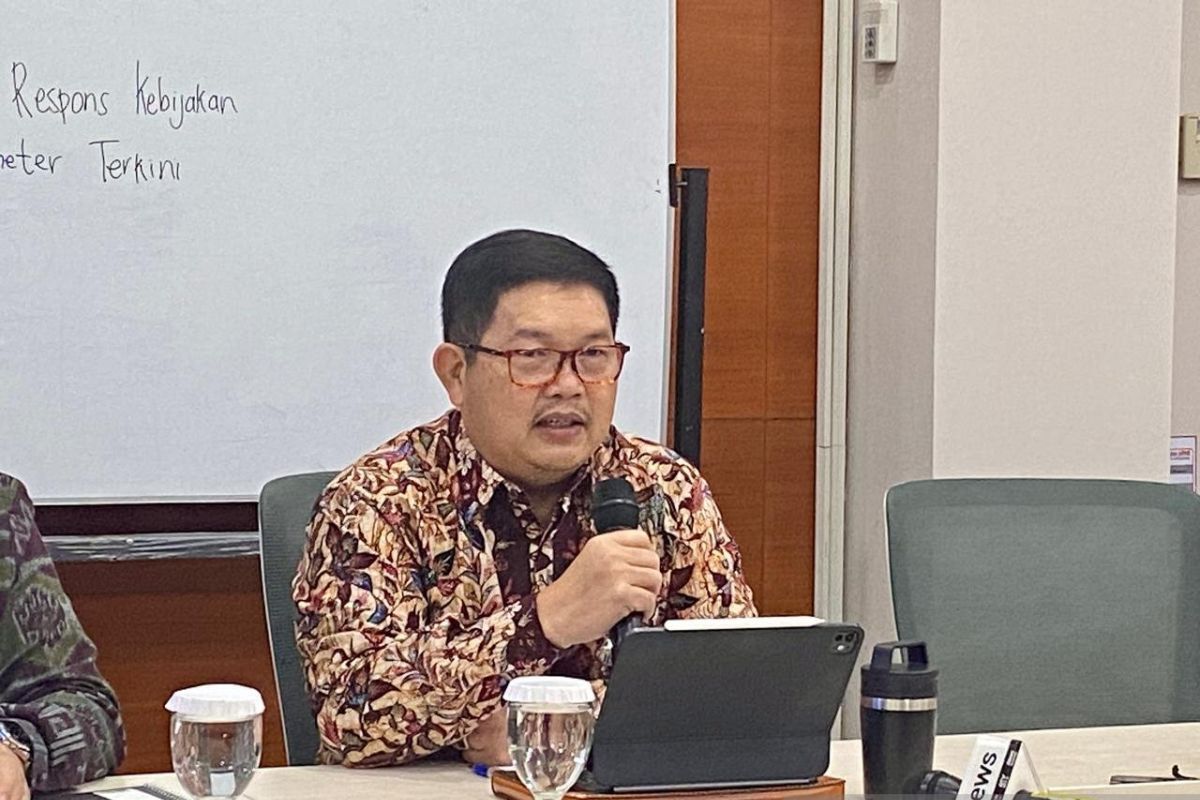
“In terms of interest, non-residents are showing interest, as demonstrated by volumes that, in my view, are not bad. We can see that rupiah-denominated asset inflows are occurring amidst global volatility,” said Erwin G. Hutapeva, Executive Director and Head of the Monetary Management and Securities Assets Department at BI, during a media briefing in Jakarta on Wednesday.
As information, BI has increased incentives for conventional hedging buy-swap instruments for underlying transactions involving foreign funding, which include portfolio inflows, foreign loans by banks, and foreign direct investment (FDI). The incentives are provided through premium reductions, moving from an initial 12.5 per cent for all tenors to 15 per cent for 3-month tenors, 20 per cent for 6-month tenors, and 25 per cent for 12-month tenors.
BI has also increased incentives for DNDF hedging instruments for underlying foreign funding transactions, covering portfolio inflows, bank foreign loans, and FDI. The premium reduction was increased from 15 per cent to 25 per cent for 6-month tenors and 30 per cent for 12-month tenors.
“The incentive is provided by reducing the swap premium price, making the hedging cost lower, so that in total, their net return can be better compared to using standard swaps, including DNDF,” Erwin explained.
He noted that currently, swap transactions are more popular, accounting for approximately 80 per cent of the volume, while DNDF accounts for 20 per cent. However, this is also due to the fact that swap incentives were introduced and implemented first, whereas DNDF incentives were implemented more recently.
According to Erwin, the benefits of this incentive policy are reflected in the capital flows entering the domestic financial market. Foreign fund inflows into Government Securities (SBN) and Bank Indonesia Rupiah Securities (SRBI) are considered quite good, even as BI gradually calibrates the SRBI instruments.
The 10-year SBN yield stood at 7.09 per cent as of 28 September 2026. With the 10-year US Treasury yield remaining above 5 per cent, the SBN yield spread against US Treasuries was recorded at 211 basis points (bps) on 18 September 2026 and narrowed to 186 bps by 28 September 2026.
According to Erwin, SBN yields at that level, when factoring in the hedging cost incentives, remain quite attractive to foreign investors compared to yields offered by several other countries. Regarding SRBI, he stated that BI continues to perform gradual calibration in terms of both yield and volume.
SRBI yields, which previously reached 7.74 per cent, dropped to 6.76 per cent during the auction on 25 September 2026. In terms of volume, the SRBI position also decreased from Rp1,097 trillion in July 2026 to Rp1,028 trillion as of 28 September 2026.
Despite the drop in SRBI yields, Erwin believes the instrument remains attractive to foreign investors due to the hedging cost incentive mechanism. “So, with the calculation of the incentives, even at 6.76 per cent (the lowered SRBI yield), it is still quite attractive in terms of spread compared to their global investment options,” he said.
Overall, Erwin stated that strong investor interest is reflected in the capital inflows. Foreign fund inflows into SBN year-to-date through the third quarter of 2026 were recorded at Rp20.51 trillion, based on settlement data up to 28 September 2026.
Meanwhile, although inflows to SRBI decreased slightly on a quarterly basis due to BI’s calibration, Erwin noted that foreign investor participation in the latest auction remained significant despite the yield being at 6.76 per cent.
Regarding the incentive costs, he stated that the central bank could not disclose the detailed calculations but assessed that the costs remain manageable. BI views these incentives as sacrificed opportunity income rather than merely a cost burden. Swap and DNDF transactions conducted by investors essentially serve as a source of revenue for BI. By providing incentives, a portion of that potential revenue is sacrificed to lower hedging costs for investors.
“When they enter swaps or DNDF, it becomes revenue for BI; that is what Bank Indonesia is sacrificing. It is not necessarily a burden in terms of cost, but rather an opportunity for revenue that we are sacrificing,” concluded Erwin.
Source: jawawa.id (https://jawawa.id/newsitem/bank-indonesia-notes-positive-foreign-investor-interest-in-hedging-cost-incentives-1790770015)
Originally published by Antara (Indonesian) (https://www.antaranews.com/berita/5765000/bi-nilai-minat-investor-asing-positif-terhadap-insentif-biaya-hedging), translated from Indonesian