
Bank Credit Grows 11.51% in May 2026, Driven by State-Owned Banks
The Financial Services Authority (OJK) has reported that national banking intermediation performance continued to show improvement in May 2026. Credit growth reached double digits, supported by a surge in investment credit distribution, which grew by nearly 22% year-on-year (yoy).
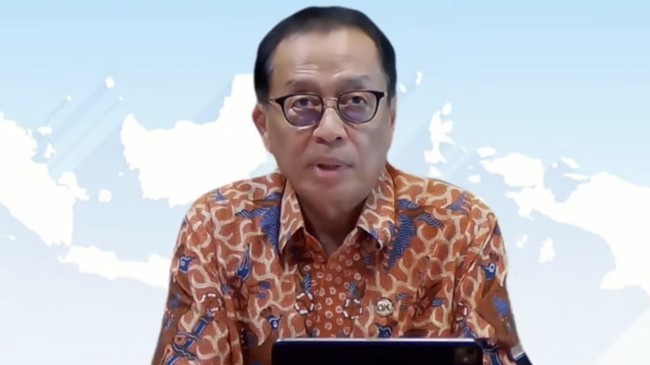
OJK Executive Head of Banking Supervision, Dian Ediana Rae, stated that banking credit as of May 2026 grew by 11.51% yoy to Rp8,918 trillion, higher than the 9.98% yoy growth recorded in April 2026. “Banking intermediation performance grew positively with a maintained risk profile,” Dian said during a press conference following the OJK Monthly Board of Commissioners Meeting on Tuesday (7/7/2026).
Based on the type of use, the highest growth originated from investment credit (KI), which surged by 21.95% yoy. Meanwhile, working capital credit (KMK) grew by 8.09% yoy, and consumer credit (KK) increased by 5.89% yoy.
From the debtor perspective, credit growth for micro, small, and medium enterprises (MSMEs) began to show signs of improvement. MSME credit grew by 0.60% yoy, higher than the 0.16% yoy recorded in the previous month.
Regarding bank groups, credit distribution by state-owned banks (BUMN) recorded the highest growth at 15.98% yoy.
In line with credit growth, the collection of third-party funds (DPK) also increased. As of May 2026, DPK reached Rp10,294 trillion, representing a 13.47% yoy growth, which is higher than the 11.39% yoy growth in April.
This growth in DPK was supported by an increase in current accounts by 20.53% yoy, deposits by 10.17% yoy, and savings by 10.21% yoy.
Regarding liquidity, Dian stated that the banking condition remains adequate. The ratio of liquid assets to non-core deposits (AL/NCD) was recorded at 108.20%, while the ratio of liquid assets to third-party funds (AL/DPK) stood at 24.74%. Both indicators remain well above the minimum thresholds set by regulators.
Meanwhile, the quality of banking assets remains well-maintained. The gross non-performing loan (NPL) ratio was recorded at 2.17%, while the net NPL stood at 0.84%. The loan at risk (LAR) ratio was recorded at 8.72%.
In terms of profitability, the return on assets (ROA) ratio was at 2.45%, while the capital adequacy of the banking industry remained strong with a capital adequacy ratio (CAR) of 23.74%.
“OJK continues to monitor the banking industry condition to ensure it remains resilient in facing various economic challenges, while maintaining the intermediation function to support national economic growth,” said Dian.