
Awaiting Prabowo's State Address Amid a 'Flood' of News from the US
Market sentiment at the end of last week was mixed. Externally, Asia-Pacific bourses mostly opened higher. Japan’s Nikkei 225 rose more than 0.2%, the Topix gained 0.29%, South Korea’s Kospi added 0.89%, and the Kosdaq climbed 0.6%.
The strengthening extended the positive performance of the previous two trading days. On Thursday (6/8/2026), the rupiah closed 0.08% stronger at Rp17,910/US$, after surging 0.50% on Wednesday.
S&P 500 Hits New Record, US Jobs Data Eases Rate Hike Concerns
The S&P 500 advanced on Friday after market participants assessed that an unexpected decline in July payrolls could prompt the Federal Reserve to hold interest rates in the near term.
The index rose 0.62% to close at a new record of 7,757.64. The Nasdaq Composite outperformed with a 1.3% surge to 26,690.62. The Dow Jones Industrial Average added 151.83 points, or 0.28%, to 54,036.93.
Wall Street posted gains for two consecutive weeks. The S&P 500, which earlier in the week closed above the 7,700 level for the first time, rose 3.6% for the week.
The Nasdaq booked a 5.2% gain, driven by a recovery in chipmaker stocks. The iShares Semiconductor ETF, or SOXX, closed the week up more than 7%. The Dow also rose nearly 3%. All three indices recorded their best weekly performance since April.
Jobs Data Far Below Estimates
The July nonfarm payrolls report showed the US economy lost 23,000 jobs. The figure was far weaker than the Dow Jones survey consensus, which projected an increase of 83,000 jobs.
The unemployment rate actually fell to 4.1% as the labour force participation rate slumped to its lowest level in more than five years. Economists had expected the unemployment rate to hold at 4.2%.
A majority of fed funds futures traders now expect the Fed to keep its benchmark rate in the 3.50% to 3.75% range at the September policy meeting, according to the CME FedWatch Tool.
The shift in expectations was rapid. A day earlier, the market still priced a 55% chance that the Fed would raise rates by 25 basis points.
“For the labour market, this figure shows conditions that are not booming and may be starting to weaken. But for financial markets, the two biggest concerns are bond yields and inflation,” said Nuveen Chief Investment Officer Saira Malik on CNBC’s Squawk Box.
According to Malik, the weak jobs data does not support the view that the Fed should resume raising rates.
Tech and Software Stocks Surge
Software stocks also led the market higher on Friday. Recent earnings reports helped ease concerns that artificial intelligence would disrupt the software industry’s business.
Cloudflare shares jumped more than 5% after the cloud-based cybersecurity company issued solid guidance for the current quarter and the full year.
Atlassian shares soared 35% after fourth-quarter revenue and adjusted profit beat expectations. The company also provided optimistic guidance.
Airbnb shares rose 17% after the accommodation rental company reported revenue and profit that were better than expected.
Oil Prices Edge Higher
Oil prices moved slightly higher as investors awaited a potential deal between the United States and Iran to reopen the Strait of Hormuz.
US Treasury Secretary Scott Bessent previously said the two countries had a chance of reaching an agreement in the near term.
West Texas Intermediate futures for September delivery rose 1.15% to settle at US$78.18 per barrel. Brent, the international benchmark, gained 1.29% to US$83.55 per barrel.
“The conclusion is that a resolution is expected to be reached before too long. If the situation changes, anxiety will return to the market,” said Terry Sandven, Chief Equity Strategist at U.S. Bank Asset Management.
“But for now, various market concerns are starting to ease,” he added.
SpaceX Shares Surge
Shares of Space Exploration Technologies, or SpaceX, jumped 12% on Friday. The gain put the company’s stock on track to close the week with a positive result after a prolonged slump.
The Elon Musk-owned company’s shares have risen nearly 19% for the week, supported by growing investor optimism about SpaceX’s fundamentals. The stock had previously fallen for four consecutive weeks.
The SpaceX rally this week was partly triggered by Argus’s decision to upgrade its recommendation on the stock from hold to buy.
The investment firm also maintained a price target of US$160 per share. That target reflects potential upside of about 39% compared with Thursday’s closing price.
Additionally, concerns about potential selling pressure from several scheduled lock-up expirations appeared to have been priced in. SpaceX shares had weakened earlier in the week on those concerns.
Indonesia’s financial markets face a busy week on 10-14 August 2026. Market participants’ main focus is on US inflation, producer prices, and retail sales, which could alter expectations for Federal Reserve rate policy.
Domestically, Bank Indonesia (BI) will release the July Consumer Survey and the June Retail Sales Survey. Both data sets will provide a picture of Indonesian purchasing power.
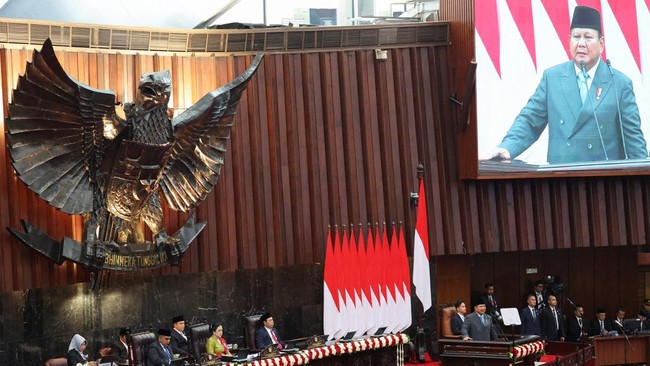
The highlight comes on Friday, when President Prabowo Subianto will deliver the State Address and submit the Financial Note and the 2026 Draft State Budget (RAPBN).
High-impact global events this week are concentrated in the US; China has no major agenda during the period.
Indonesian Consumer Confidence
Bank Indonesia is scheduled to release the July Consumer Survey today, Monday (10/8/2026). Initial projections suggest the Consumer Confidence Index (IKK) may fall to 116 from 117.8 in June.
The June IKK had previously fallen from 120.9 and reached its lowest level since September 2025. The weakness stemmed mainly from declining public assessments of current economic conditions, purchases of durable goods, and job availability.
Consumer expectations for income, job availability, and business activity over the next six months also weakened. Nevertheless, the index remains above 100, indicating consumers are still in an optimistic zone.
The market will watch whether the decline in consumer confidence begins to ease or continues into July. A better-than-projected IKK could support consumer, retail, automotive, banking, and telecommunications stocks.
Conversely, a deeper decline could reinforce concerns about purchasing power and consumer credit demand. Such conditions could also reduce optimism about household consumption growth in the third quarter of 2026.
Indonesian Retail Sales
BI will continue the domestic agenda by releasing the June Retail Sales Survey on Tuesday (11/8/2026).
Retail sales are projected to grow 1.8% year-on-year, reversing a 3.9% contraction in May. May sales contracted for the second consecutive month and marked the deepest decline since May 2023.
The previous weakness was visible in sales of food, beverages and tobacco, clothing, and household equipment. Sales of information and communication devices also remained deeply contracted. Meanwhile, automotive parts sales continued to grow, albeit at a slower pace.
A return of retail sales to positive territory would signal that household consumption is beginning to recover. This is important because consumption is the largest contributor to Indonesia’s economy and underpins the revenue of many domestic listed companies.
However, if sales contract again, the market may conclude that cost-of-living pressures are still limiting public spending. Such conditions could weigh on retail, consumer goods, automotive, and banking stocks that depend on consumer credit growth.
US Home Sales
The US will announce existing home sales for July on Tuesday (11/8/2026). Consensus expects sales to edge down to 4.07 million units from 4.09 million units on an annualised basis.
In June, existing home sales fell 2.4% month-on-month and came in below market expectations. Declines occurred in the South, Midwest, and West regions, while the Northeast recorded an increase.
Housing inventory fell to 1.56 million units, equivalent to 4.6 months of supply. At the same time, the median home price rose 1.8% year-on-year to US$440,600, the highest in more than a year.
Housing data provides a picture of the impact of high interest rates on US households and the economy. Further weakening in sales could raise expectations of Fed easing.
However, an excessively deep decline also risks reinforcing concerns that high interest rates are beginning to exert greater pressure on economic activity.
US Consumer Inflation
The biggest agenda item this week is US consumer inflation for July, to be released on Wednesday (12/8/2026) at 19:30 WIB.
Annual inflation is expected to ease to 3.4% from 3.5%. On a monthly basis, consumer prices are expected to rise 0.1% after falling 0.4% in June.
Core inflation, which excludes food and energy prices, is projected to slow to 2.5% year-on-year from 2.6%. On a monthly basis, core inflation is expected to increase 0.2% after being unchanged in the previous period.
June inflation fell sharply due to easing energy price pressures. Petrol and fuel prices declined, offsetting increases in food and shelter prices. Core inflation also slowed from 2.9% to 2.6%.
Because the previous decline was largely helped by energy, the market will watch whether price pressures in services and shelter also ease. Core inflation is considered a better gauge of underlying and persistent price pressures.
Higher-than-expected inflation could boost the US dollar and US Treasury yields as the likelihood of Fed easing diminishes. That scenario could pressure the rupiah, government bonds, and emerging-market equities.
Conversely, inflation in line with or lower than projections could strengthen hopes for rate cuts. Such conditions could support banking, property, technology, and other interest-rate-sensitive sectors.
US Producer Inflation
The US will release the July Producer Price Index (PPI) on Thursday (13/8/2026) at 19:30 WIB. Headline PPI is expected to rise 0.1% month-on-month after falling 0.3% in June.
Core PPI is projected to grow 0.2%, the same as the previous period. On an annual basis, producer inflation is expected to ease to around 5% from 5.5%.
In June, annual producer inflation fell to 5.5% from 6% and came in below expectations. Although declining, the figure remains quite high and indicates that cost pressures at the producer level have not fully dissipated.
PPI is often viewed as an early indicator of price pressures that producers may later pass on to consumers. A higher-than-expected increase, especially after a hot CPI, could reinforce concerns that the disinflation process is stalling.
Conversely, a weak PPI could reinforce positive sentiment if consumer inflation is also contained. That combination could pressure the dollar and US bond yields while providing room for the rupiah and the JCI to strengthen.
State Address and RAPBN 2027 Financial Note
The attention of the public, businesses, and investors will turn to the Joint Session of the DPR, MPR, and DPD on Friday (14/8/2026). President Prabowo Subianto is scheduled to deliver the State Address and outline the government’s fiscal policy direction through the RAPBN 2027 and the Financial Note.
This year’s session is being held earlier than usual. Previously held on 16 August, it has been brought forward by two days because 16 August 2026 falls on a Sunday.
In the morning, Prabowo will deliver the State Address, which will include an evaluation of the government’s performance throughout 2026 as well as development priorities going forward. In the afternoon, the President will deliver the Government’s Introductory Statement on the 2027 State Budget Bill along with the Financial Note.
The two agendas are important because they can provide signals about Indonesia’s economic and fiscal direction in 2027.
Through the State Address, the market will scrutinise which programmes will be the government’s priorities. One area of attention is the Free Nutritious Meals (MBG) programme, given its impact not only on state spending but also on public purchasing power, absorption of domestic products, and economic activity in various regions.
However, investors’ greatest attention will be on the RAPBN 2027.
Through the Financial Note, the government will provide a picture of how much the state will spend, sources of state revenue, the deficit, and financing strategies for various priority programmes.
Several macro assumptions will also be in focus, including economic growth targets, inflation, the rupiah exchange rate, oil and gas lifting, and the Indonesian Crude Price (ICP).
For investors, these figures provide clues about the direction of fiscal policy and its potential impact on financial markets. For businesses, the assumptions can provide a picture of demand prospects, investment, production costs, and business opportunities throughout 2027.
Previously, the government and the DPR’s Budget Committee (Banggar) agreed on several initial frameworks for the RAPBN 2027 in discussions on the 2027 Macroeconomic Framework and Fiscal Policy Principles (KEM-PPKF).
One agreed target is 2027 economic growth in the range of 5.8%-6.5%.
Inflation is set in the range of 1.5%-3.5%. The rupiah exchange rate is assumed to be in the range of Rp16,800-Rp17,500 per US dollar, with the 10-year government bond yield projected at 6.5%-7.3%.
“With the 2027 development targets and indicators, it has been agreed that the 2027 economic growth target reaches 5.8% to 6.5%,” said Wihadi at a DPR Plenary Session, as quoted on Friday (3/7/2026).
The range will serve as one of the government’s foundations in preparing the initial draft of the RAPBN 2027 and the Financial Note.
After being presented at the Joint Session, the 2027 State Budget Bill will be discussed further with the DPR, including through Commission XI, before being enacted into law at the end of October 2026.
Thus, 14 August 2026 is not merely an annual ceremony. For the market, the day is a moment to read the direction of the Prabowo administration’s economic policy: how aggressively state spending will be pushed, where the money will come from, and which sectors will be the government’s priorities in 2027.
US Retail Sales
US retail sales for July will be announced on Friday (14/8/2026) at 19:30 WIB. Consensus expects sales to grow 0.1% month-on-month, slowing from 0.2% in June.
Sales excluding vehicles are expected to increase 0.2% after falling 0.2%. Meanwhile, the sales group used in calculating consumption in GDP is projected to remain solid.
In June, retail sales continued to grow due to increases in vehicle sales, online trade, electronics, and sporting goods. However, lower energy prices pressured petrol station receipts. Excluding petrol, sales actually grew more strongly.
An above-forecast figure would indicate that US consumption remains solid and can support economic growth. However, overly strong consumption could also slow the decline in inflation.