
Aneka Tambang (ANTM) Shares Remain Promising Amid MSCI Storm
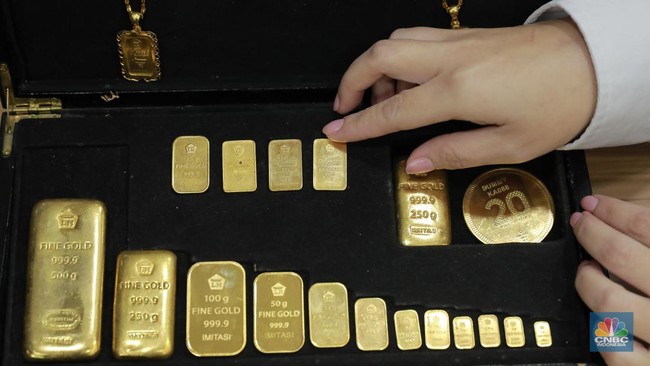
Jakarta, CNBC Indonesia — Shares in PT Aneka Tambang Tbk (ANTM) remain promising despite the company’s removal from the MSCI Global Standard Index in July 2026. Its fundamentals remain strong, supported by its gold and nickel businesses, downstreaming projects and the potential for substantial dividend payments.
Analysts say the share-price correction could present an opportunity for long-term investors to accumulate ANTM shares.
Phintraco Sekuritas analyst Alrich Paskalis Tambolang said MSCI-related pressure could prompt portfolio adjustments and increase volatility in ANTM shares, regardless of the company’s fundamentals. Although the price correction creates an opportunity to accumulate shares, there is not yet a solid support level.
“Investors should wait for prices to stabilise and foreign selling pressure to ease before entering gradually,” he said on Thursday, 22 October 2026.
He said ANTM’s fundamentals remained relatively strong. In the first half of 2026, the company recorded net profit of Rp6.91 trillion, up 34 per cent year on year, with gold the main contributor to sales.
Its nickel business and downstreaming projects could also drive medium-term growth. However, performance remains sensitive to commodity prices, sales volumes and the successful execution of projects.
Historically, he said, ANTM distributed around Rp5.05 trillion in dividends for the 2025 financial year, or Rp209.99 per share, equivalent to 70 per cent of that year’s net profit. In assessing the next dividend, investors should consider full-year 2026 earnings, cash flow and capital expenditure, budgeted at around Rp6 trillion.
“Dividends could support sentiment, but may not be enough to offset selling pressure caused by MSCI,” he said.
From a technical perspective, he said the Rp2,350–2,400 range could be watched as a support level for gradual accumulation, with near-term targets of Rp2,800 and Rp3,000. If support breaks, investors should be alert to further weakness.
Key catalysts to watch, he said, include developments in the MSCI issue, gold and nickel prices, third-quarter results and progress on downstreaming projects. Investors should not focus solely on the share-price decline, but wait for confirmation of a trend reversal.
Nafan Aji Gusta, senior market analyst at Mirae Asset Sekuritas, said ANTM’s removal from the MSCI Global Standard Index would create short-term mechanical selling as global passive funds adjust their portfolios through rebalancing. However, the selling is technical and does not indicate a deterioration in the company’s operating performance.
He said such outflows often create mispricing, with shares falling more than their intrinsic value. This could create an opportunity for medium- to long-term investors to accumulate gradually and buy on weakness at more attractive prices.
He added that downstreaming projects rely heavily on strategic partnerships for funding, limiting the burden of capital expenditure on internal cash flow and leaving the company’s financial position safe and flexible.
“Strong cash flow and profitability make expectations of substantial dividend payments very realistic. ANTM has historically maintained a high dividend payout ratio, and an attractive projected dividend yield could act as a catalyst for a share-price recovery,” he said.
He said the dividend appeal could draw domestic institutional investors focused on returns back into the stock, while helping to contain further selling by foreign investors.
In the short term, volatility and further price corrections remain possible until the market has absorbed the full impact of the MSCI rebalancing. Nevertheless, strong fundamentals and dividend prospects make ANTM a suitable portfolio-diversification option over the medium to long term, provided investors buy gradually to minimise exposure to price fluctuations.
Panin Sekuritas analyst Elandry Pratama said pressure on the shares did not mean ANTM’s fundamentals were deteriorating. “Accumulation opportunities may emerge once the valuation becomes attractive, but investors should proceed gradually and wait for prices to stabilise. In current conditions, it is important to distinguish capital-flow-driven selling from a change in the company’s business prospects,” he said.
Fundamentally, he said, ANTM remained attractive because of its gold and nickel businesses and its downstreaming potential. Gold can support revenue when prices are high, while nickel and downstreaming projects offer medium- to long-term growth opportunities.
He also said the prospect of substantial dividends could be a positive catalyst, but any payout would depend on net profit, cash flow, dividend policy and capital expenditure needs. Dividend expectations should not be based on profits alone without accounting for the funding required for expansion. Dividends could help sustain investor interest, but might not be enough to revive the share price if selling pressure and negative market sentiment persisted.
Muhammad Wafi, head of research at Korea Investment & Sekuritas Indonesia (KISI), said ANTM’s share prospects depended more on gold prices and earnings than on the Jakarta Composite Index (IHSG). The risk of passive selling in ANTM shares was small, he said, although the stock could still be affected if foreign investors sold Indonesian assets more broadly.
“Sentiment-driven corrections can be an opportunity to accumulate gradually,” he said.
Source: jawawa.id (https://jawawa.id/newsitem/aneka-tambang-antm-shares-remain-promising-amid-msci-storm-1792651919)
Originally published by CNBC Indonesia (https://www.cnbcindonesia.com/market/20261022124646-17-778566/prospek-saham-aneka-tambang--antm--di-tengah-badai-msci), translated from Indonesian