
Analysts Reveal Prospects for ANTM Shares, Set This Target!
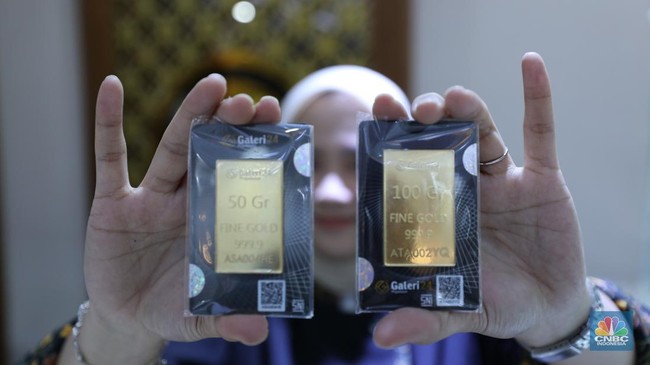
Several analysts have shared their insights regarding the prospects of PT Aneka Tambang Tbk (ANTM), also known as Antam. According to various experts, ANTM shares remain worth collecting, given the company’s very strong business fundamentals.
As is well known, ANTM does not rely solely on gold, but also utilises nickel, bauxite, and alumina as part of its business diversification. This strategy makes ANTM more resilient to price fluctuations in any single commodity.
It is therefore unsurprising that ANTM’s performance through the first quarter of 2026 continued to grow, with net profit reaching IDR 3.66 trillion, an increase of 58%, even though global gold prices had recently dipped from their record highs.
“Antam remains prospective because the diversification into gold and nickel acts as a natural hedge,” said Muhammad Wafi, Head of Research at Korea Investment & Securities Indonesia, as quoted on Thursday (2/7/2026).
Wafi’s confidence in ANTM’s prospects is well-founded. He noted that current gold prices remain historically high with thick margins, alongside the long-term potential for nickel downstreaming.
On the other hand, the recent decline in Antam’s gold prices has driven public investment interest and increased gold instalment purchases, which is positive for the retail bullion segment (Logam Mulia). Furthermore, volumes have the potential to rise because prices are more affordable, even though margins per unit might be thinner compared to peak prices.
“The impact is positive, but the magnitude needs careful observation because the retail bullion segment’s contribution to total revenue is smaller compared to the wholesale and nickel segments. It is significant for volume and brand visibility, but not necessarily proportional to the bottom line,” Wafi concluded.
Echoing Wafi’s sentiment, Adrian Djie, an Equity Research Analyst at Kiwoom Sekuritas, also stated that ANTM’s current fundamentals remain very strong, supported by the trend of increasing gold sales every year.
“We assess that ANTM’s future prospects remain bright, supported by management’s target to drive gold sales to match or exceed the 2024 record,” said Adrian.
As reported, ANTM recorded an increase in gold sales reaching IDR 66.47 trillion throughout 2025, a 15% increase compared to IDR 57.56 trillion in 2024.
This increase in sales boosted the company’s revenue by 22% to IDR 84.64 trillion in 2025, compared to IDR 69.19 trillion in the previous year.
“The gold segment is the largest contributor to ANTM’s revenue. However, in our view, retail participation does not entirely increase ANTM’s performance significantly, although it certainly provides a boost. We recommend a ‘buy’ with a long-term target of 4,800,” stated Adrian.
For information, in trading on Friday, 3 July 2026, ANTM shares closed up by IDR 170 or 6.16% at IDR 2,930.